Zero Hedge

Watch: Prosecutor Claims It's 'Wrong, But Not Illegal' To Jerk-Off In Front Of Kids

Watch: Prosecutor Claims It's 'Wrong, But Not Illegal' To Jerk-Off In Front Of Kids

Authored by Steve Watson via Modernity News,

A Soros-backed Florida prosecutor told the public that a man pleasuring himself on a park bench in front of children was "wrong," then insisted it is not a crime.

Ninth Judicial Circuit State Attorney Monique Worrell used a press conference to defend her office's refusal to charge Kevin Chapman, 61, after his arrest at Kit Land Nelson Park in Apopka.

A father and his two-year-old were at the splash pad. Witnesses, park staff, photos and video put Chapman on a bench with his hand in his shorts, facing the children, for minutes. The park manager said his shorts dropped when he stood up.

"All things that are wrong are not illegal, and I'm not standing before you today telling you that what happened in that park was wrong," said the prosecutor, adding "But I am standing before you today telling you that I trust the word of the attorney who was assigned to this case when he said, although those actions were wrong, he could not prove beyond a reasonable doubt that they were illegal."

Florida law is not a riddle. Section 800.04(7) makes it a second-degree felony for an adult to intentionally masturbate, expose genitals in a lewd manner, or commit another sexual act without contact in the presence of a child under 16.

That is up to 15 years.

Florida Attorney General James Uthmeier put it in a formal letter: her office not only skipped pretrial detention, it declined to charge him at all and called the case "not suitable for prosecution."

"Central Florida deserves better than a state attorney who prioritizes the guilty over protecting the innocent," Uthmeier said. "She gave this guy a free walk in the park, and now other kids are in jeopardy of having a tragic incident happen to them."

Worrell's counter was that the toddler supposedly did not clock what was happening, and that no other adult saw the genitals clearly enough. In other words, a man can sit in a children's park and finish the job so long as the two-year-old is too young to give a courtroom speech about it.

She then turned the argument into a grievance about Gov. Ron DeSantis, who suspended her in 2023 for dereliction of duty. Voters put her back. The children at the splash pad did not get a vote.

"It is clear that the underlying intention here is to unjustly remove me from office, yet again," she said. Of Uthmeier: "He struts and shouts as if volume can mask ignorance, but all he's proven is that he's a punchline in a job that demands serious leadership."

In 2020, Our Vote Our Voice PAC poured about $1.5 million into ads for Worrell. A million of that came from Democracy PAC, created by George Soros. This is what that project produces: a prosecutor who can look at a man wanking on a park bench in front of a splash pad and reach for the phrase "not suitable for prosecution."

The same office also dropped local charges against Thomas Dolgos, 47, who possessed and shared videos of infants and toddlers being raped. Statewide prosecutors were already on the case. After the local charges vanished, Dolgos fled and was grabbed at the Canadian border. Uthmeier's description of that file was blunt: "videos of toddlers getting raped and abused."

Of course, the core issue here is scumbags masturbating in public.

As we've highlighted, women and children across Europe keep meeting foreign men who treat trains, beaches, bus stops, pools, metro cars and church doors as private booths. Nobody voted for it. Nobody should have to live with it.

The examples are bountiful.

In Forest Park Brussels last May, a man started masturbating in front of a group of women. One woman hit him with a water bottle and ran. He threw a shoe at her face. When he was confronted, a witness said he offered the philosophy in one sentence: "She's half-naked; I don't see why I shouldn't be able to masturbate."

Another woman described "not a shred of shame or remorse." Police only grabbed him two days later at Place de la Bourse.

That is the same shrug Worrell dressed up as legal reasoning. He said the quiet part. She put it on a podium.

In another incident, young Spanish girls filmed a migrant masturbating in front of them on the mainland.

A Spanish woman described a Moroccan doing it on a train while she sat with her boyfriend; they stayed quiet because they thought he might turn violent. When she named his origin, other women called her racist.

In Palma, a young Moroccan man was filmed masturbating in broad daylight on Calle Industria in the Molinos district, "in front of numerous minors who were going to Mass." Theo man stood at a doorway with his genitals out, porn playing on his phone, while families, children and elderly people moved toward church. People shouted at him. He kept going. Police were called. He left before officers found him.

In the same city, National Police arrested a Moroccan man after he filmed himself masturbating while watching two underage girls on Playa de Palma.

In February, a 22-year-old Moroccan was pulled off an EMT bus in Palma after masturbating in front of passengers, including children as young as five.

In Ceuta, a Moroccan man in his 40s or 50s masturbated in front of children at Fuente Caballos beach. Bathers were close to handling it themselves. Police had to fight him as they attempted to remove him. He admitted exhibitionism. The sentence was an eight-month fine of five euros a day.

Video from a packed Italian shore showed an African migrant masturbating among families and children while men nearby watched and did nothing.

Another clip showed the same act at an outdoor pool in front of children; when the man was confronted and lost the fight, a white woman threw herself in front of him to shield him.

Near Portofino, an African man did it on the sand in front of Langosteria di Paraggi, again with families and children present.

The Paris Metro produced the same spectacle in a packed carriage.

Hannover produced it in front of families and young girls. The locations change. The audience does not.

Britain is not exempt. A Scottish woman named Margaret called a BBC morning show and described a foreign man masturbating in front of her at a bus stop. She said she was disappointed in herself for lacking the courage to stop it.

In Newcastle, witnesses said a repeat offender rubbed himself in a packed city-centre fast food restaurant with children present, then did the same at the Burger King inside Newcastle Central Station during half-term.

A British woman filmed an illegal migrant touching himself at a bus stop; when he was spotted, he made a shooting gesture. He already had a record for the same thing.

Police in West Yorkshire later tried to "reassure the public" after a Leeds bus-stop exposure video resurfaced.

And on and on and on it goes...

And on...

Children are not a gray area. A park bench facing a splash pad is not an acceptable arena for solo sexual pleasure. A church door at Mass is not a safe space for a wrong un with a phone full of porn. If a justice system cannot say that out loud and then act, it has stopped being a justice system. It has become a protection racket for the worst scum of the Earth.

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden Thu, 09/10/2026 - 08:45

Futures Slide As Yields, Oil Spike Ahead Of PPI

Futures Slide As Yields, Oil Spike Ahead Of PPI

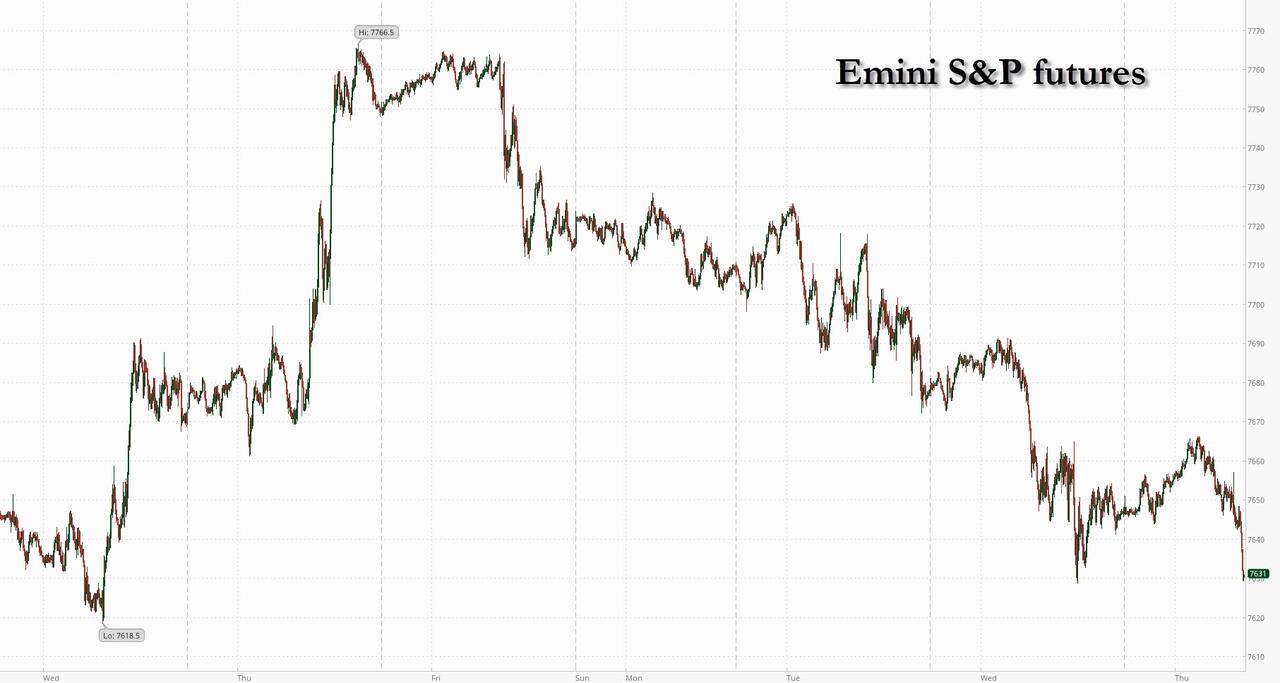
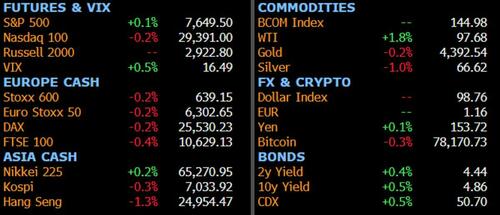
US stock futures slumped for a 3rd consecutive day, unable to find traction, and trading at session lows with tech underperforming as Treasury yields pushed higher keeping risk appetite firmly in check ahead of the latest print on US factory prices and earnings from Oracle. As of 8:15am ET, S&P futures are down 0.2%, with Nasdaq futures lagging, and down 0.5%. Pre-market, MegaCap Tech stocks are mixed, led by AAPL and META +1.0%. Overnight, TSMC reported a 53% increase in monthly sales amid strong AI infrastructure demand. Incremental macro news flow were largely muted since yesterday’s close: Trump promised $5k division if GOP wins the midterm, which sparked fresh fiscal stability concerns and pushed yields to fresh 3 year highs, as the 10Y tops 4.88%. The USD reversed an earlier drop to trade at session highs as the Yen slumps. Commodities are mixed: Oil higher (WTI +1.7%), while precious metals are lower; base metals and Ags are higher. US economic data slate includes weekly jobless claims and August PPI (8:30 a.m.) and August existing home sales and July wholesale inventories (10 a.m.). Fed speakers remain in external communications blackout period ahead of Sept. 15-16 FOMC meeting
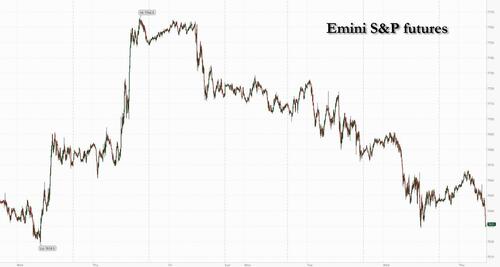
In premarket trading, Mag 7 stocks are mixed but fading fast: Meta rises 1.3% as JPMorgan upgrades to overweight, citing upside potential after the social media giant launched its AI assistant (Apple +1.1%, Alphabet +0.2%, Microsoft little changed, Amazon -0.1%, Nvidia -0.5%, Tesla -0.7%

  • Copper stocks are falling after Reuters reported that the White House has not ​yet made a decision on refined copper tariffs as it weighs concerns of higher prices raising manufacturing costs against the potential benefits of encouraging more domestic mining, citing two people familiar with the matter.
  • AeroVironment (AVAV) rises 4% after the drone maker reported revenue for the first quarter that beat the average analyst estimate.
  • American Eagle (AEO) falls 14% after the apparel firm’s second-quarter total comparable sales fell short of the average analyst estimate. Analysts note that strength at its aerie brand was more than offset by weakness at AE.
  • Cooper (COO) tumbles 16% after the healthcare supplies maker cut its adjusted earnings-per-share and revenue guidance for the full year. Analysts note weakness in the firm’s CooperVision unit weighing on its sales forecast.
  • JetBlue (JBLU) falls 2% after the airline cut its available seat miles forecast for the third quarter.
  • Kinetik (KNTK) climbs 4% as the energy pipeline company partly owned by Blackstone is in the early stages of exploring options, including a sale, according to people familiar with the matter.
  • Macy’s (M) slips 1% as investors weigh much better-than-expected comparable sales and adjusted EPS in the second quarter against a less robust third-quarter guidance.
  • Navan (NAVN) slumps 15% after the software company gave an outlook that analysts said pointed to weaker trends in the second half of the year, despite overall solid growth.
  • Rackspace Technology (RXT) climbs 13% after the company said it had joined the Nvidia Cloud Partner Program.

In other corporate news Citadel Securities told regulators that prediction market contracts linked to publicly-traded companies should be overseen by the SEC. Boring Co. secured $3 billion in fresh funding backed by the UAE, valuing Elon Musk’s tunneling startup at $23 billion.

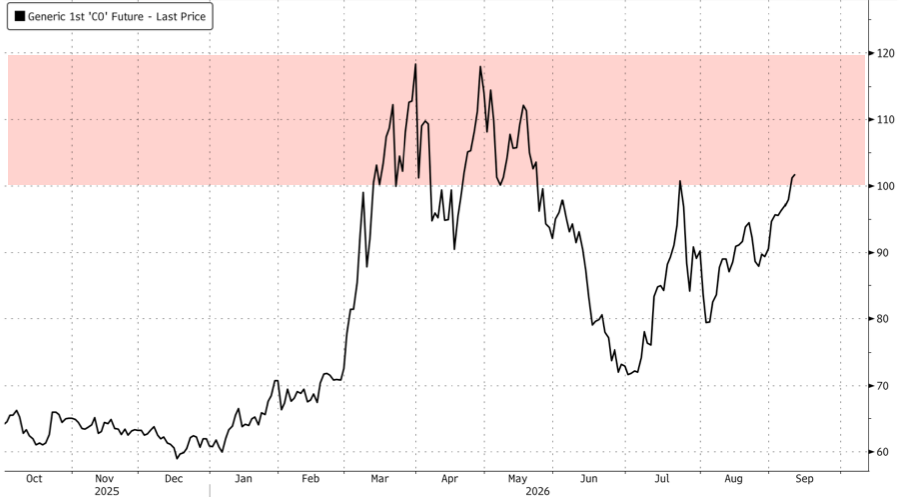
Sentiment remains muted as inflationary signs grow: Brent is now trading above $103 (with Shanghai trading at $115!) as Iran vowed it was prepared for a more intense war, LME copper futures hit new records, and global tanker freight rates reached all-time highs.

Investors are also bracing for a busy calendar that could provide fresh catalysts for markets. The packed agenda comes after global yields climbed to the highest in years as the war in the Middle East pushed oil prices higher, prompting traders to bet on tighter monetary policy across the globe.

First up is the latest European Central Bank interest rate decision, with a hike already priced in and the focus instead on guidance. Earnings from Oracle Corp. will offer a fresh read on the outlook for artificial intelligence.  

Meanwhile, the August producer price index could offer clues on the course of inflation for the rest of the year and what it means for US rates. Today’s PPI number, followed by CPI on Friday, are key for market direction. With PPI components feeding directly into the Fed’s preferred inflation gauge and Fed’s Waller saying that the August data will heavily influence his decision, a hot print could materially reprice September rate-hike odds, currently at 61%. Stocks currently have greater sensitivity to bond yields, with S&P 500 equity risk premium relative to Treasury yields at lowest since 2002.

“Today’s PPI report matters, but probably not enough on its own to change the Fed’s decision next week,” said Santiago Mateo Yanguas at CaixaBank AM. “That said, a significant upside or downside surprise could still move markets today by shifting expectations for the rate path beyond the next meeting, particularly in Treasury yields and interest rate-sensitive sectors.”

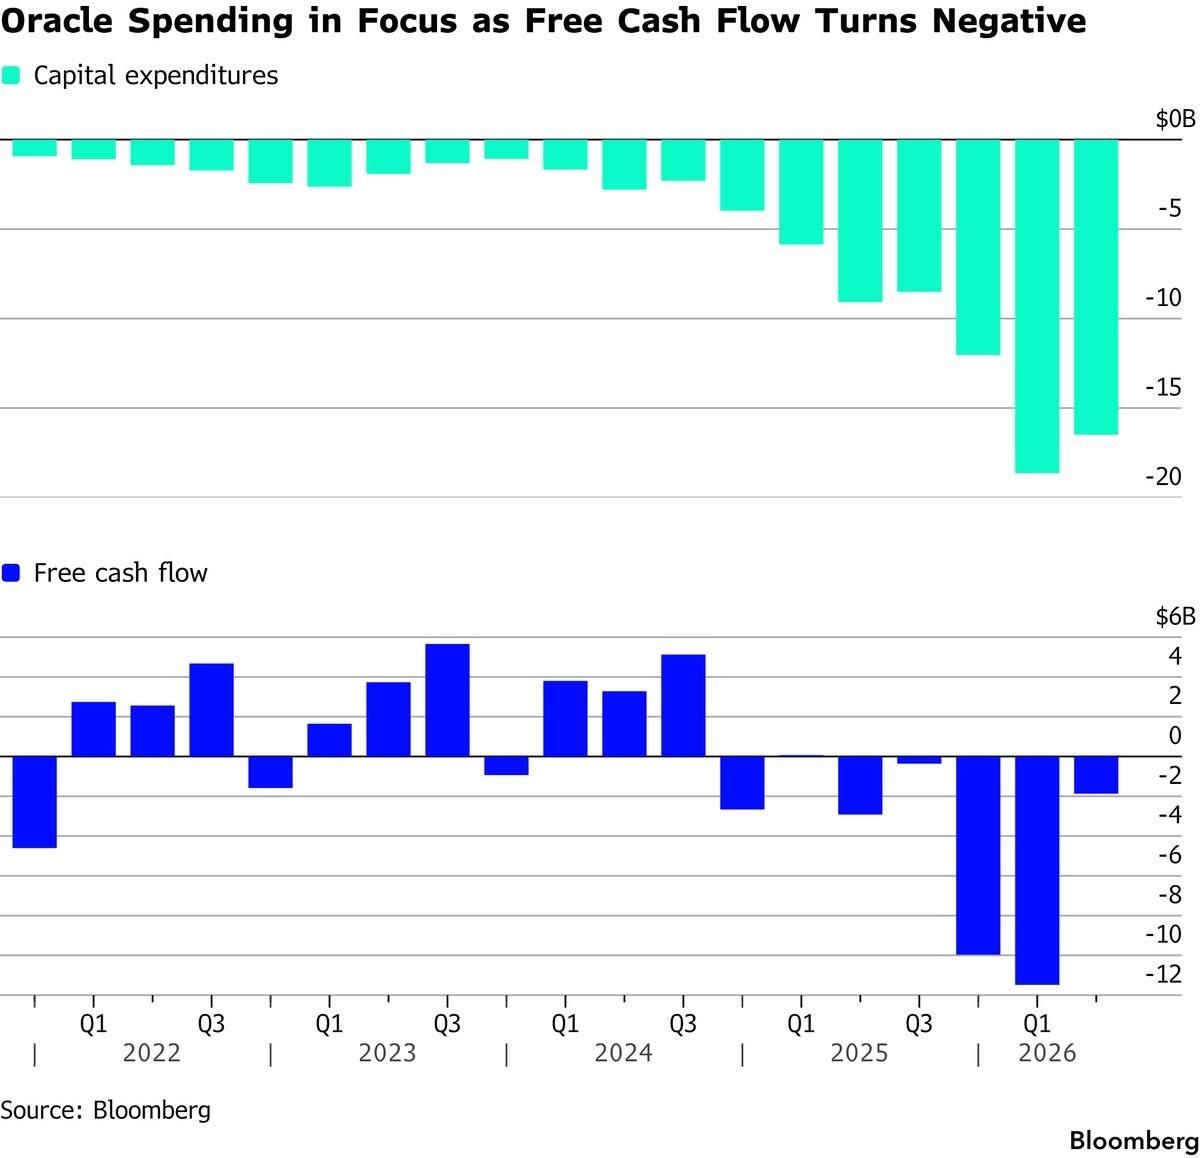
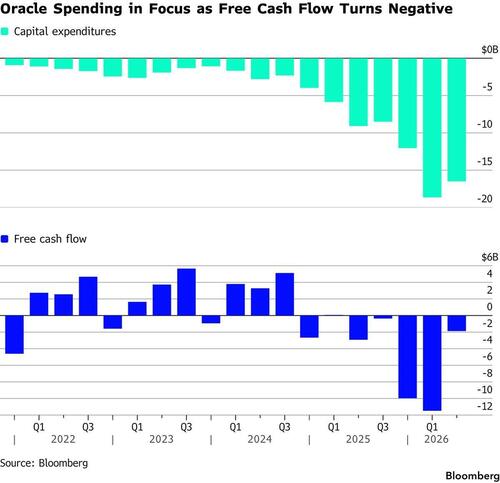
Oracle reports after the US close with its shares down 17% this year, sharply underperforming tech peers as traders punished the firm over concerns about heavy capital spending and leverage. While cloud unit sales are projected to have more than doubled in the first fiscal quarter, recent market moves show that strong earnings aren’t always enough to win investors over. Separate figures from Adobe Inc. will offer another window into how software giants are navigating the challenge from AI.
“While quarterly results may trigger short-term volatility, we see the underlying earnings trend as the more important driver of long-term equity performance,” said Francisco Simon at Santander Asset Management. “The structural growth story remains intact, and that is ultimately what matters.”

Meanwhile, markets largely shrugged off President Donald Trump’s promise to give adult US citizens a $5,000 dividend if Republicans retain control of both houses of Congress.

“Markets appear to assign a very low probability to the measure becoming law, given the significant fiscal cost and the political hurdles it would face in Congress,” said CaixaBank’s Yanguas. “Unless the proposal gains tangible legislative support, investors are likely to treat it more as campaign rhetoric.”

Still, while Trump's offer was met with skepticism by the market, it adds to concerns about erratic policymaking at a time when Bessent is striving to keep yields down. Yesterday’s buyback announcement disappointed many who had expected more than the up to $6 billion announced: The “Treasury brought a pea shooter to a tank battle,” said Elias Haddad, Global Head of Markets Strategy at Brown Brothers Harriman.

Still, the ‘Trump dividend’ would cover the cost of a shiny new iPhone. Part of the sticker shock had been well flagged, with memory prices for smartphones surging as the AI buildout sucks up supply. Hyperscaler spending will be back in the spotlight after the close when Oracle reports — it’ll be a big test of market tolerance for AI spending given the company’s massive debt load.

There’s no signs of a slowdown in the AI buildout yet. TSMC posted the second fastest year-on-year monthly sales print for 2026, with the company struggling to meet overwhelming demand. Microsoft’s CFO said at an investor conference that Azure was supply constrained, while AI chipmakers in China are reportedly raising processor prices.

The upside in oil has also weighed on equities with the Stoxx 600 down 0.2% after erasing an earlier gain. European shares slipped for a third day ahead of an ECB meeting that’s expected to deliver an interest-rate increase and could offer clues on further policy tightening. Here are the biggest movers Thursday:

  • FirstRand shares gained as much as 4.5%, the most since May, after the South African lender reported full-year results, which JPMorgan analysts said reflect “robust” momentum
  • MP Evans Group gained as much as 6.5%, to the highest since May, after the Indonesian palm oil producer announced an acquisition of new land in Kota Bangun
  • Genfit shares climbed as much as 12%, the most in over two months, after the biopharmaceutical firm outlined the commercial prospects for its non-invasive diagnostic test for MASH (metabolic dysfunction-associated steatohepatitis), sparking price-target upgrades
  • D’Ieteren shares rose as much as 6.4%, the most in more than four months, after adjusted pretax profits rose in the first half
  • Corbion advanced as much as 5.7%, to the highest since Feb. 2025, as Oddo BHF lifts its price target on the Dutch food ingredients firm to a joint Street-high
  • AB Foods shares fell as much as 11%, the most since January, after the Primark owner reduced its profit guidance for the Sugar and Grocery divisions
  • Genus shares fell as much as 9.8%, the most since February, after full-year revenue at the livestock breeding and genetics group missed analyst expectations
  • Hemnet fell as much as 9.6%, the most since April, after the Swedish property listings platform announced it will pause its share buyback program of up to SEK600m in ordinary shares
  • Fevertree Drinks fell as much as 6.5%, the most in more than a year, after the beverage company reported first-half earnings that came in shy of expectations

“We don’t think that the ECB would be more hawkish than current pricing,” noted Mohit Kumar at Jefferies. “We expect Lagarde to keep the future path of monetary policy data-dependent and not lean into a series of rate hikes.”

Asian stocks fell, tracking losses on Wall Street, as oil prices surged past $102 a barrel and intensified concerns that inflationary pressures would keep interest rates elevated. The MSCI Asia Pacific Index dropped as much as 1.3%, the most in a week, before paring some losses as chipmakers recovered from session lows. TSMC, Delta Electronics, Tencent and Alibaba were among the biggest drags on the gauge. South Korea’s Kospi closed down 0.3%, while most other benchmarks in Asia, including Taiwan and Hong Kong, traded lower. After being down much of the day, Japan’s Topix recovered and ended 0.2% higher, with Recruit Holdings contributing the most to the gains.  “Oil price fluctuations and the upside of some of the near-term escalations that we’ve seen have really been some of the key risks that market has to fathom as we head toward the the end of this year,” said Yuting Shao, senior director for global macro strategy at Manulife Investment Management. Earlier this week, MSCI’s Asia stock gauge approached near June’s record high as sectors beyond technology drove the rally. But renewed Middle East tensions have driven oil prices higher, with Brent crude holding gains after Iran said it was prepared for a more intense war with the US. 

In FX, the Bloomberg Dollar Spot Index is flat. The krone is the weakest of the G-10’s, falling 0.3% against the greenback.

In rates, the downside in Treasuries has pushed US 10-year yields up 3 bps to 4.87%, the highest since October 2023. Advancing energy prices weigh on Treasuries and front-end gilts, which have underperformed during London morning. With Treasury front-end yields about 1-2bp higher on the day and 10-year about 4bp higher near 4.855%, 2s10s and 5s30s spreads are about 2bp wider. Gilts lead the selloff in European government bonds with UK two-year borrowing costs rising to the highest since November 2023. US session highlights include August PPI data, 30-year bond auction and results of the 10- to 20-year buyback shortly after 2 p.m. New York time. 

WTI crude oil futures remain higher by about 1.7% after rising as much as 1.9%; Brent crude topped $102 a barrel amid signs US war on Iran will be protracted

Treasury auction cycle concludes with $22 billion 30-year bond reopening; Wednesday’s 10-year note auction drew strong demand as measured by its clearing yield 1.5bp lower than indicated by the WI level at the bidding deadline. WI 30-year yield near 5.31% is 9.4bp higher than last month’s new-issue auction result, a 0.4bp tail. IG dollar issuance slate includes Kommunalbanken 3-year offering; 16 borrowers priced $23 billion of US investment-grade bonds Wednesday, pushing two-day volume above $61 billion. Issuers paid about 4bps in new issue concessions on deals that were 3.1 times covered.

In commodities, Brent crude futures rise over 2% and above $103 for the first time since July with Iran ready for a more intense war. Oil prices did fall earlier in the session, providing a modicum of support to bonds after Wednesday’s selloff but that proved short lived.Spot silver falls 1% while gold is little changed.

US economic data slate includes weekly jobless claims and August PPI (8:30 a.m.) and August existing home sales and July wholesale inventories (10 a.m.). Fed speakers remain in external communications blackout period ahead of Sept. 15-16 FOMC meeting

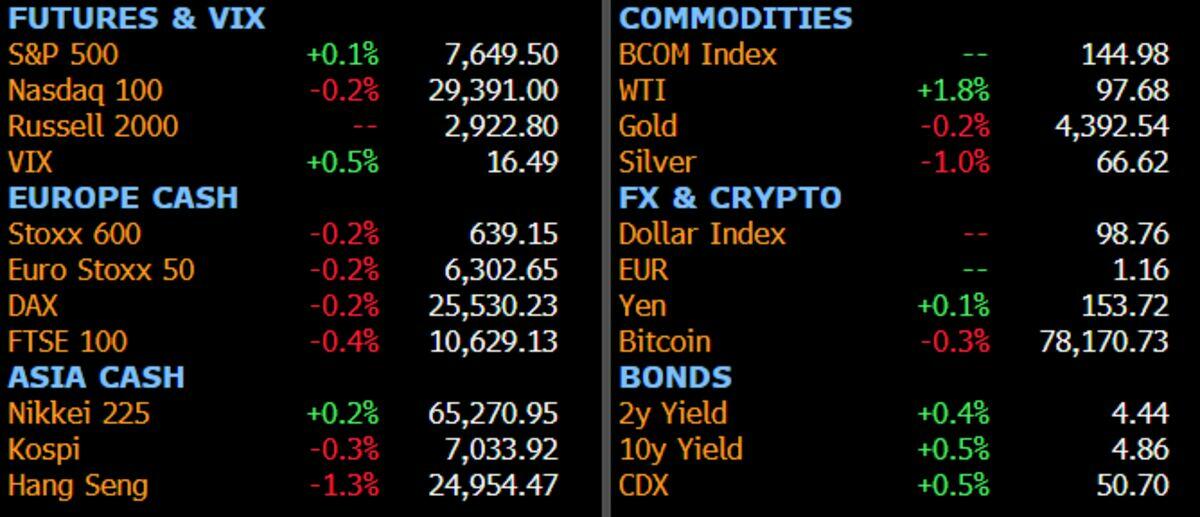
Market Snapshot
Top Overnight News

  • Trump on Wednesday suggested his Iran war might end after the mid-terms, but some of his top advisors warn it could last the duration of his presidency, potentially extending the conflict past Inauguration Day in January 2029. WSJ
  • Donald Trump promised $5,000 for every US adult if Republicans retain Congress, which must be spent in the US and will cost well over $1 trillion. The move signaled mounting concern over affordability and fiscal discipline as voters sour on the economy and Iran war. BBG
  • US Treasury Secretary Bessent touted tax cuts, job increases, trade rebalance and Trump accounts during his speech at the RNC Midterm Convention.
  • Within weeks of Iran’s closure of the Strait of Hormuz, once Saudi Arabia’s primary export route for oil, the kingdom turned to Plan B: bypassing the strait by ramping up exports through pipelines to Red Sea. NYT
  • The South Korean government is nearing the announcement of a major energy investment project in the U.S. to support America’s artificial-intelligence build-out, a long-awaited development of the trade deal struck between Washington and Seoul last year. The deal, potentially worth more than $100 billion, envisions South Korea financing the construction of up to eight nuclear power plants and a natural-gas project. WSJ
  • The popularity of high-risk bets among investors looking to cash in on South Korea’s artificial-intelligence boom has caused concern at the central bank. A surge of investment in leveraged exchange-traded funds tied to tech titans such as Samsung Electronics and SK Hynix generated significant volatility in the domestic stock market, the Bank of Korea said, calling for stronger oversight and regulation of leveraged ETFs as they risk sowing instability. WSJ 
  • The ECB is widely expected to raise rates for the second time since the Iran war sent energy prices soaring. The focus will be on signals from Christine Lagarde as markets see at least two more hikes. BBG
  • The Bank of Japan may eventually be forced to raise interest rates rapidly if inflation accelerates given the country's loose financial conditions, board member Kazuyuki Masu said, warning of price risks ‌that solidify the chance of a September hike. In a closely watched speech ahead of next week's policy meeting, Masu warned of broadening price pressures that have pushed underlying inflation "very close" to its 2% target. Reuters
  • US PPI likely firmed in August after a renewed pickup in commodity prices. Consensus expects a 0.4% monthly increase. BBG
  • TSM reported record monthly revenue for August on Thursday, as demand for chips used in artificial intelligence applications remained strong. The world’s largest contract chipmaker posted revenue of $514.8 billion New Taiwan dollars ($16.35 billion) for last month, up 53.3% from a year earlier and 10.1% from July. CNBC
  • BofA Total Card Spending (w/e 5th Sept) +7.8% Y/Y (prev. +3.7% W/W). BofA said that the surge in spending growth was likely due to base effects from the shift in Labour Day timing and a rebound in gas prices.
  • A US AI safety bill could be introduced next week, Semafor reported citing sources.
  • A US Republican-led Senate subcommittee is investigating OpenAI's handling of the Hugging Face breach in July, Axios reported.
  • S&P500 EPS growth in Q2 2026 was ~30% year / year excluding the "other income" related to some private investment stakes. Earnings for the hyperscalers and the AI infrastructure companies benefiting from their capex spending increased by 54% year / year in Q2, accounting for about 50% of S&P 500 EPS growth during the quarter. However, earnings growth for the rest of the market has also been strong and accelerating. Excluding the Energy sector profits that were boosted by higher oil prices, the rest of the S&P 500 posted year/year EPS growth of 14%: GS FICC

A more detailed look at global markets courtesy of Newsquawk

APAC stocks were mostly lower following the losses stateside, where all major indices declined as yields and oil prices climbed, with Brent crude topping USD 100/bbl for the first time since July. ASX 200 underperformed amid broad-based weakness across sectors and with the downside led by materials, mining, resources, and tech. Nikkei 225 was pressured alongside a higher yield environment and ongoing rate hike expectations, while BoJ board member Masu also stuck to the hawkish hymn sheet. KOSPI declined at the open but was off today's worst levels as SK Hynix rebounded from intraday lows. Hang Seng and Shanghai Comp conformed to the subdued mood across the region in the absence of bullish drivers and after the PBoC conducted open market operations, but at a paltry amount of CNY 3bln.

Top Asian News

  • PBoC's Lu Lei said the Bank will refine the RRR framework and conduct open-market operations more flexibly and precisely.
  • Japanese MOF Official Sato said the government is not considering buying back JGBs at this point.

European bourses are mixed, with Italy's and Spain's main indices (IBEX 35/FTSE MIB +0.2%) outperforming while the FTSE 100 (-0.4%) is the slight laggard. Light in terms of newsflow this Thursday morning, with focus being on US data (PPI on Thursday, CPI on Friday) and the ECB. Sectors point to a mixed picture. Autos top the sector pile, followed by Travel & Leisure and Insurance. To the downside is Tech, with Basic Resources and Construction rounding out the sector laggards.

Top European News

  • German HICP Final (Aug MM) 0.2% vs. Exp. 0.2% (Prev. 0.9%).
  • German HICP Final (Aug YY) 2.9% vs. Exp. 2.9% (Prev. 2.8%).
  • Norwegian Core CPI (Aug YY) 3.0% vs. Exp. 3% (Prev. 2.7%).
  • Norwegian Core CPI (Aug MM) -0.5% vs. Exp. -0.4% (Prev. 0.8%).
  • Swedish GDP (Jul MM) -0.8% (Prev. -0.2%).
  • Italian Industrial Production (Jul MM) 0.7% vs. Exp. 0.3% (Prev. -1.1%).
  • Italian Industrial Production (Jul YY) 0.0% vs. Exp. -0.6% (Prev. -0.6%).
  • Spanish Industrial Production (Jul YY) 2.3% (Prev. 1.1%); M/M 0.6% (exp. 0.2%).
  • UK RICS House Price Balance (Aug) -28 vs Exp. -30 (Prev. -30, Rev. -29).

FX

  • Snapshot: G10s are mixed against the flat USD. The Kiwi incrementally gains, whilst the JPY posts slight losses. Ultimately, price action has been sideways this morning, with focus on US PPI and the ECB later.
  • DXY trades sideways and holds within a 98.70 to 98.82 range. There has been a lack of pertinent newsflow for the USD this morning, and it ultimately awaits US PPI this afternoon. There may be added focus on today’s report, with traders looking for any clues heading into the CPI report on Friday. Jobless Claims are also on the docket. Yields continue to trudge higher, as energy benchmarks remain above USD 100/bbl. However, as mentioned in yesterday's piece, the USD has largely ignored the higher yield environment. Much of this is likely due to the recent JPY strength, and also some fiscal-related fears creeping into markets. Moreover, markets will likely avoid making firm bets on the USD ahead of CPI (tomorrow) and the Fed next week.
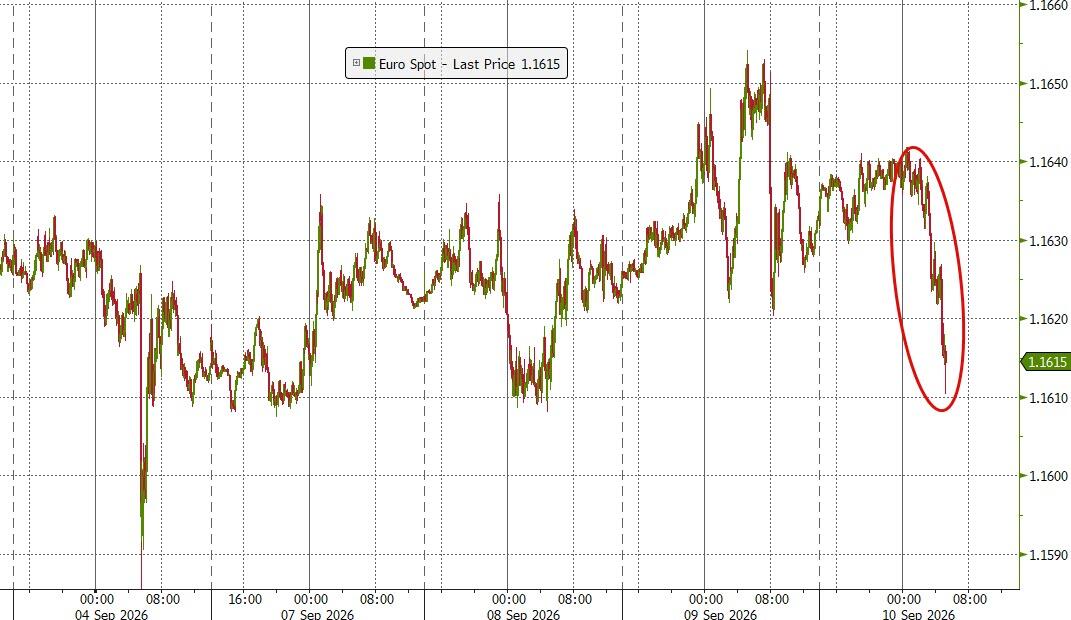
  • EUR trades within a 1.1629 to 1.1641 range, and holds near its 200-DMA at 1.1633. EUR action will be dictated by the ECB this afternoon, where the Bank is set to deliver a 25bps hike. Aside from the decision, focus will be on the updated staff projections (inflation to be upwardly revised), and any guidance for action later in the year. ING opines that President Lagarde could use her presser to push back on some of the markets’ hawkish bets, which currently price in another hike this year. However, the likelihood is that the President will reiterate her data-dependent and non-committal approach.
  • JPY has been in focus for the past couple of weeks, with USD/JPY falling c. 4.5% since the start of the month. The pair is a bit more contained this morning, despite hawkish commentary from BoJ’s Masu, who stated that he expects to continue raising rates given current accommodative conditions. USD/JPY currently holds at the mid-point of a 153.28 to 153.74 range.

Fixed Income

  • Despite a slightly firmer start for Bunds and USTs, as energy took a relative breather in late-APAC/early-European trade, fixed has reverted into the red and continues to falter as energy climbs once more with Brent above USD 102/bbl.
  • USTs are once again below the 107-00 mark, and to an incremental WTD base of 106-29, which is also a contract low. Amidst this, yields are marginally firmer across the curve, with the 2yr to a 4.41% peak and the 10yr to 4.86%. Aside from the energy move, upside is a function of participants digesting commentary from President Trump at the RNC where he pledged a USD 5k dividend following a strong mid-term performance; while unlikely to occur, as it would need Congressional approval, the payment would cost in excess of USD 1tln and add further pressure to already strained public finances.
  • Today, for the US, the docket is dominated by PPI and weekly claims. Note, the PPI release comes ahead of Friday’s CPI, which could well define the outcome of the September Fed. Thereafter, we look to supply and given, counterintuitively, the upside seen in yields on the Treasury buyback announcement on Wednesday, the 30yr tap today may garner extra attention. For reference, the 10yr (after the buyback announcement) was very strong, with the mentioned yield move beforehand potentially providing some additional concession into it.
  • Bunds also lower, by just over 20 ticks at a 121.11 base, matching the low from Wednesday. Specifics for the region light, no move to final CPI earlier. Ahead, the docket is dominated by the ECB. A hike is widely expected, but the decision may not be a unanimous one. Additionally, we look for any deviation in the statement and/or Lagarde from the data-dependent, meeting-by-meeting approach, to a potential hawkish tilt given recent developments. On this, the 2027 & 2028 HICP forecasts will be key. However, recent moves in crude and TTF mean they are likely already somewhat stale and the expected upward revision to the forecasts is perhaps not sufficient. Something that may be elaborated on by Lagarde.
  • The UK sells GBP 5bln 4.625% 2030 Treasury Gilt: b/c 3.24x, average yield 4.786%, tail 0.3bps.
  • Italy sells EUR 7.75bln vs exp. EUR 6.5-7.75bln 3.00% 2029, 3.35% 2033 and 2.15% 2072 BTP.

Commodities

  • WTI Oct and Brent Nov futures eke out mild gains, with prices continuing to be underpinned by the Middle Eastern situation, which shows no signs of abating. The former resides in a current USD 95.37-97.84/bbl range (vs yesterday’s 93.76-96.93/bbl range) whilst the latter trades in a USD 100.19-102.72/bbl range (vs yesterday’s 98.80-101.87/bbl parameter). Upside is somewhat capped by the delayed Private Inventory report, which showed a smaller draw than expected, with the DoE slated for today on account of Monday’s US holiday. Dutch TTF front-month has mounted EUR 80/MWh after finding an earlier base just above EUR 78/MWh, with prices continuing to be underpinned by Middle East supply woes alongside heating demand heading out of summer.
  • Metals are subdued as higher energy prices keep the complex capped from a growth perspective, although participants await fresh drivers. Ahead, the ECB is unlikely to sway metals much, although US PPI could have an impact, particularly on precious metals. Spot gold resides in a narrow USD 4,388-4,435/oz range after finding support near yesterday’s USD 4,434/oz high. Note that yesterday, the bullion found support at its 100 DMA (today at 4,340/oz). 3M LME copper trades around record highs in a current USD 14,742.65- 14,870.78/t range.
  • In terms of geopolitics, US President Trump said he thinks war with Iran will end immediately after the election and that they will win the war with Iran, while Iran said they are ready for a more intense war if required. Several explosions were heard yesterday in Iran's Qeshm and Sirik, while an oil tanker was reportedly being targeted in the Strait of Hormuz. Meanwhile, mediator Pakistan warned Iran to restrain Yemen’s Houthi militants after a rise in attacks on Saudi Arabia, while Houthis attacked Saudi cities with ballistic missiles and drones, and Saudi Arabia reportedly conducted airstrikes in Yemen. Pakistan's Foreign Minister said that there are no discussions right now regarding plans to act under the Makkah Defence Agreement, but when the time comes, they will act on the agreement.
  • US Weekly Private Inventory Data (bbls): Crude -0.3mln (exp. -1.3mln), Gasoline -1.9mln (exp. -1.8mln), Distillate +2.0mln (exp. -0.2mln), Cushing -0.3mln.
  • US Energy Secretary Wright said the current refining capacity is a bigger problem than crude oil supply.
  • IEA's Birol said their new report shows global coal demand is now set to rise by 1.2% in 2026.
  • Russia's Ryazan oil refinery (~350k BPD) has been idle since a September 6 drone attack, according to sources.
  • Oman OSP for November-loading crude set at USD 119.30/bbl (prev. USD 87.84/bbl in October).
  • Czech PM Babis said the EU should halt the ETS1 carbon allowances system and delay ETS2 due to the higher energy prices.

Trade/Tariffs

  • US trade official said China is ramping up their purchases and is on track to fulfil farm purchases ahead of Chinese President Xi's Washington visit, according to SCMP. It was separately reported that China bought 1mln tons of US soybeans ahead of Xi's visit to the US, according to sources.
  • The South Korean government is considering artificial intelligence investments as part of its trade agreement with the Trump administration, WSJ reported, with a deal that could potentially be worth in excess of USD 100bln.
  • China's MOFCOM said China and the US are in consultations on arrangement for a USD 30bln reciprocal tariff cut framework, Xinhua reported.
  • China is extending the anti-dumping probe into pecans from both Mexico and the US.

Central Banks

  • BoJ Board Member Masu said one‑ to two‑year real interest rates remain negative and that they need to keep the price trend from going above 2%, while he added that the BoJ is expected to continue raising interest rates given current accommodative financial conditions. Masu said Japan is no longer in deflation, so real interest rates should be moved out of negative territory as soon as possible, and noted that the policy rate is approaching the estimated neutral-rate range, so prices, employment and financial conditions must be monitored carefully. Furthermore, he said with Japan’s financial conditions still accommodative, the BoJ could be forced to raise rates rapidly if inflation accelerates, and that the BoJ must raise rates further and move its policy rate within the estimated neutral-rate range so it can conduct policy flexibly.
  • In further comments, BoJ's Masu said underlying inflation is gradually approaching 2%, but currently does not expect it to rise substantially above that level. When asked about a 50bps hike, Masu said the bank should proceed cautiously with hikes. On the Yen, Masu stated that they will closely assess the yen’s appreciation and rising crude oil and global food prices at next week’s policy meeting. Masu added that they have emergency market operations as a tool, but that is only saved for exceptional moves in JGB markets.

Geopolitics: Middle East

  • US President Trump said they will win the war with Iran and that oil prices will go down as soon as they win, while he suggested calling the Hormuz Strait the Trump Strait. Trump said 'may have to give them a shot at Pickaxe Mountain' and advised Iran not to get cute as the US would have to hit them very hard.
  • Top White House advisers have raised privately with US President Trump the prospect that the Iran conflict could last through the remainder of his term, according to WSJ.
  • CBS reporter Jennifer Jacobs noted that multiple US military aircraft suffered damage in strikes the prior night on the Salti Air Base in Jordan.
  • Several explosions were heard in Iran's Qeshm and Sirik, with the sounds reportedly originating from the sea, according to Fars News Agency. Furthermore, IRNA cited official sources that stated areas in Sirik were hit by projectiles, although SNN reported that no points in Sirik have been targeted.
  • Pakistan's Foreign Office spokesperson said the Makkah defence agreement is a defensive alliance focused on deterrence, with expansion not currently planned until its foundations are solidified. The Ministry added that there are no discussions right now regarding plans to act under the Makkah Defence Agreement but that when the time comes, they will act on the agreement.
  • An Iranian lawmaker said Iran can take "special measures" in response to the IAEA's resolution and may consider action.

Geopolitics: Russia

  • Russia's Defence Ministry said they struck Ukraine's Black Sea port of Chornomorsk and two ships near Odessa.
  • Ukrainian President Zelensky said Ukrainian forces struck eight infrastructure targets supporting Russian military operations over the past 24 hours, including an oil refinery in Russia’s Yamalo-Nenets region and a seaport in Dagestan.
  • Ukraine's Air Force said attack drones targeted Zaporozhzhia and that drone groups were headed to Dnipro and Kamienske.
  • Poland’s Operational Command said military aviation remains active and ground-based air defense and radar systems are on alert due to potential threats to Polish airspace from Russian drone activity in western Ukraine.
  • NATO allies have reportedly caught Russian submarines training to debut a secret weapon which could disable critical undersea cables, without leaving evidence, Reuters reported.

US Event Calendar

  • 8:30 am: Sep 5 Initial Jobless Claims, est. 205k, prior 206k
  • 8:30 am: Aug 29 Continuing Claims, est. 1780k, prior 1779k
  • 8:30 am: Aug PPI Final Demand MoM, est. 0.4%, prior 0%
  • 8:30 am: Aug PPI Ex Food and Energy MoM, est. 0.3%, prior 0.2%
  • 8:30 am: Aug PPI Final Demand YoY, est. 5.3%, prior 4.7%
  • 8:30 am: Aug PPI Ex Food and Energy YoY, est. 4.6%, prior 4.2%
  • 10:00 am: Aug Existing Home Sales, est. 3.98m, prior 4.06m
  • 10:00 am: Jul F Wholesale Inventories MoM, est. 1.3%, prior 1.3%

DB's Jim Reid concludes the overnight wrap

Markets had another eventful session yesterday, with stagflation fears mounting after Brent crude oil moved above $100/bbl for the first time since July. That was primarily driven by the latest strikes between the US and Iran, and the moves saw investors price in faster rate hikes and pushed bond yields to multi-year highs. On top of that, Treasuries saw further declines after the US Treasury Department confirmed they were buying back up to $6bn of longer-dated Treasuries, which fell short of some estimates. So by the close, that meant the 10yr Treasury yield (+5.2bps) hit a post-2023 high of 4.84%, whilst the 10yr bund yield (+7.6bps) hit a post-2011 high of 3.44%. And in turn, that pressured risk assets as well, with the STOXX 600 (-1.41%) posting its worst day in the last two months, whilst the S&P 500 (-0.48%) fell for a third day running. So even though we’re just over a week into September, it’s already living up to its reputation as one of the toughest months of the year for markets.  

As in recent days, the main catalyst for the oil move was the latest US-Iran strikes. So on Tuesday evening, we heard that the US had destroyed five Iranian tankers. And then as we went to press yesterday morning, Iran said they’d targeted 2 US vessels and 8 oil tankers in the Persian Gulf in retaliation. For investors, that news raised fears about a further escalation, and Bloomberg also reported that a senior Iranian official said Iran was ready for a more intense war if the US continued its attacks. So that raised doubts that the Strait of Hormuz would reopen soon, and there was a separate WSJ report overnight that White House advisers had privately raised the prospect with President Trump that the war could continue for the remainder of his term. So Brent crude (+3.36%) jumped to $101.21/bbl by the close, its highest level since May. And investors also moved to price in a more protracted period of high oil prices, with the 6-month Brent future (+1.55%) rising to its highest since early June, at $86.09/bbl.  

Whilst Brent crude rising above $100/bbl took up the main headlines, the inflation concerns were exacerbated by the latest moves in natural gas prices. In particular, European natural gas futures (+4.49%) closed at their highest level since 2022, at €79.25/MWh, and they even traded above €80/MWh at one point. That was partly driven by the US-Iran news, but prices took a further leg higher after the Governor of Russia’s Yamalo-Nenets autonomous district reported that there was a fire at an industrial site. That region is a major hub for Russian gas, and Ukraine said later that its drones had struck two gas condensate plants there. So the reports added to concerns about global gas supplies in the months ahead, particularly with the Strait of Hormuz still blocked.

With oil and gas prices still rising, that led to mounting speculation about faster rate hikes from central banks. So in the US, futures raised the probability of a September hike next week from 61% on Tuesday to 63% this morning. In part, that’s down to the inflationary impulse from energy, but the extent of the moves has also led to concerns about second-round effects, whereby inflation could broaden out away from energy. Meanwhile in Europe, investors also priced in a more hawkish path for the ECB, with an additional +9.0bps of hikes priced in by the June 2027 meeting, meaning that 86bps of further hikes are now priced by then. So that feeds into the concern we wrote about on Monday (link here), where several asset classes are vulnerable to the impact of building inflationary pressures and a faster tightening cycle from central banks.  

Those commodity moves put upward pressure on bond yields, but the rise then accelerated after the US Treasury Department announced they’d be purchasing up to $6bn of longer-dated Treasuries in their initial buyback operation. As a reminder, the Treasury delivered a surprise announcement in mid-August that they’d “at least double” the size of these operations, having previously planned to buy back $2bn before. But we didn’t know exactly how big that would end up being, so there was some uncertainty about how the market would react. But ultimately, the $6bn announcement saw yields rise across the curve, having fallen short of some estimates beforehand. So the 2yr yield (+3.7bps) ended the session at 4.43%, its highest since July 2024, and the 10yr yield (+5.2bps) moved up to 4.84%, the highest since October 2023. Meanwhile, the 30yr yield (+4.3bps) was up to 5.29%, still slightly beneath its recent closing peak of 5.31% on August 17.  

Over in Europe, there were even bigger moves in yields, given the continent’s greater exposure to higher energy prices. As a result, yields hit new multi-year highs across countries and maturities. For instance, the 2yr German yield (+7.2bps) rose to 3.06%, its highest since June 2024, whilst the 10yr bund yield (+7.6bps) hit another post-2011 high of 3.44%. Indeed, it now isn’t far away from the 2011 Euro Crisis peak of 3.49%, and if that’s exceeded, it would take yields up to levels not seen since 2009. Meanwhile in France, the 10yr OAT yield (+10.9bps) surged to a post-2008 high of 4.34%, and Italy’s 10yr BTP yield (+11.0bps) hit a post-2023 high of 4.29%. Here in the UK, there were fresh records too, with the 10yr yield (+8.9bps) at a post-2007 high of 5.26%, whilst the 30yr yield (+6.8bps) hit a post-1998 high of 5.87%.  

Looking forward, European rates will stay in the spotlight today, as we have the ECB’s latest policy decision at 13:15 London time. For the decision, they’re widely expected to deliver a 25bp rate hike today, taking their deposit rate up to 2.5%. So that would be the second rate hike of this cycle, following on from the initial hike back in June. But given that a rate hike is already priced in today, the focus will instead be on the path forward, including their latest economic forecasts. Our European economists think that there’ll be small upward revisions to the GDP projections for 2026 and 2027, along with higher headline inflation for 2027 and 2028. Otherwise, their view is that the ECB won’t give formal guidance today, and will instead repeat the “data dependent, meeting by meeting, no precommitment” mantra. For more details, see their full preview here.  

Ahead of all that, equities had a rough session yesterday, as the combination of geopolitical risk, higher energy prices and higher yields all weighed on the major indices. So in the US, that meant the S&P 500 (-0.48%) fell for a third day running. The breadth of the moves was even more negative, as the S&P saw 404 decliners, the most since June. Meanwhile, energy (+1.09%) was the only sector in the index to register an advance, up to a record high. Meanwhile in Europe, there were even bigger declines given the continent’s greater energy exposure, with the STOXX 600 (-1.41%) experiencing its worst session in two months, alongside bigger losses for the DAX (-1.66%) and the CAC 40 (-1.94%).  

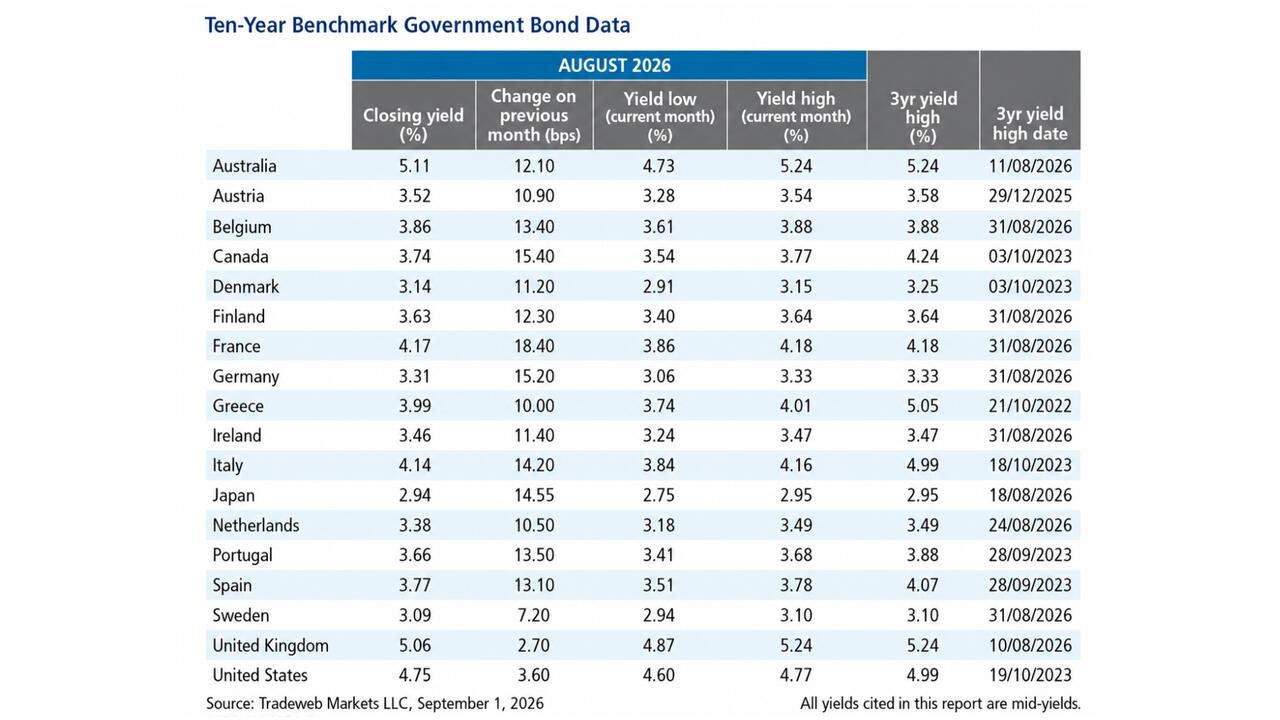
Overnight, that weakness has continued in Asian markets, with further rises in bond yields. That includes Australia’s 10yr yield (+6.6bps), which is up to a post-2011 high of 5.27%, whilst Japan’s 10yr yield (+5.4bps) is up to 2.93%. Meanwhile for equities, the major indices have lost ground across the region, with the S&P/ASX 200 (-1.43%) and the Hang Seng (-1.29%) posting the biggest declines, alongside smaller falls for the Nikkei (-0.54%), the CSI 300 (-0.42%), the Shanghai Comp (-0.35%) and the KOSPI (-0.36%). Nevertheless, there have been signs of stabilisation overnight, with S&P 500 futures (+0.16%) pointing to a modest recovery after three consecutive declines for the index.  Finally, we also heard from the BoJ’s Masu overnight, who said that they’d “continue to raise the policy interest rate”, and that “What is most vital from now on is to ensure that the underlying inflation rate does not significantly exceed 2%.” So that cemented market expectations that the Bank of Japan would deliver another hike at their meeting next week.  

Looking at the day ahead, the main highlight will be the ECB’s policy decision, along with President Lagarde’s subsequent press conference. Otherwise, US data releases include PPI inflation for August, the weekly initial jobless claims, and existing home sales for August.

Tyler Durden Thu, 09/10/2026 - 08:27

EUR Drops As ECB Hikes Rates (As Expected); Raises Inflation Outlook, Sees Downside Growth Risks

EUR Drops As ECB Hikes Rates (As Expected); Raises Inflation Outlook, Sees Downside Growth Risks

The European Central Bank increased interest rates for the second time since the Iran war broke out in February, responding to signs inflation is set to stay well above 2%.

The deposit rate was lifted by a quarter-point to 2.5% on Thursday, as predicted by almost all economists in a Bloomberg survey.

“The conflict in the Middle East continues to generate inflation pressures, and inflation is set to remain well above target for an extended period,” it said in a statement.

“The outlook remains highly uncertain, with risks to the upside for inflation and to the downside for economic growth.”

GUIDANCE:

As widely expected, the Governing Council left his language on the future rate path unchanged, repeating the mantra of being “well-positioned" and following a "data-dependent and meeting-by-meeting approach."

That actually leaves all options open for the coming months, and it seems likely that Lagarde will try to do the same later.

INFLATION

  • Inflation is set to remain well above target for an extended period.

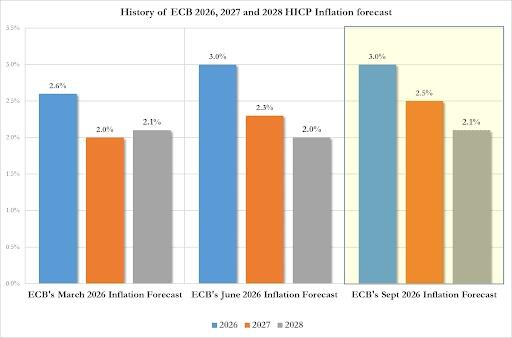
The ECB raised its inflation outlook for the next two years...

  • *ECB SEES 2027 INFLATION AT 2.5%%; PRIOR FORECAST 2.3%

  • *ECB SEES 2028 INFLATION AT 2.1%; PRIOR FORECAST 2%

  • *ECB SEES 2027 INFLATION EX-FOOD/ENERGY AT 2.6%% VS 2.5%

Despite more encouraging signals, though, as underlying inflation and a closely watched gauge of services prices retreated. Wage pressures also eased.

ECONOMIC OUTLOOK

  • The outlook remains highly uncertain, with risks to the upside for inflation and to the downside for economic growth.

Thursday’s move puts euro-area policymakers further ahead of their peers in reacting to the energy-price surge that’s produced the fastest inflation in almost three years.

Traders see the ECB doing more, pricing two further hikes by mid-2027.

That contrasts with the Federal Reserve and the Bank of England, which are yet to tighten monetary policy over the fighting in the Middle East and may refrain again next week.

Interestingly, despite the relative hawkishness, the EUR is fading this news...

Patrick Ernst, a strategist at J.P. Morgan Private Bank:

“The ECB moved as anticipated, but what accompanied that rate decision matters more. In keeping the door open to further tightening, policymakers made clear that an energy-led inflation risk is still very much in play. One hike is not a ceiling. The odds of another before year-end have risen.”

President Christine Lagarde, who continues to be linked with an early departure from her role, will face journalists at 14:45 p.m. in Berlin.

Tyler Durden Thu, 09/10/2026 - 08:27
Hike Or Hold? Debating The Coming Fed Decision

Hike Or Hold? Debating The Coming Fed Decision

Authored by Michael Lebowitz via Real Investment Advice,

Heading into the September 16 FOMC meeting, the debate over whether the Fed should raise rates or hold is heated. To help you appreciate the range of views, we present this article as a courtroom exercise. We will let the prosecution make its case for a rate hike, and the defense make its case for a hold. We will render our verdict after both sides present their cases.

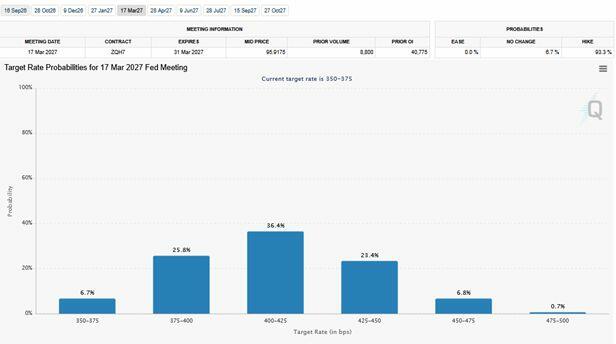
To set the stage, Fed funds futures are pricing in a 60% chance of a September rate hike, with further hikes possible at subsequent meetings. The graph below shows the market is pricing in a 36% chance of two rate hikes by mid-March 2027, with roughly equal 25% chances of three hikes or only one.

The Prosecution's Case: Rate Hike

With the strong August BLS employment data, the case for a hike now has three legs.

The first is Fed Chair Kevin Warsh's Jackson Hole address on August 28. His policy-related comments were direct: he wants to restore credibility to his pledge to get inflation back to 2% in short order. Below are comments we wrote in Warsh Makes A Hawkish Pivot:

Warsh was blunt in his assessment of inflation. He signaled the Fed may not be done fighting inflation, saying financial conditions didn't look restrictive enough to him and that recent benign inflation readings hadn't convinced him the trend was improving meaningfully. Per Warsh's speech:

"And while this summer's PCE and CPI readings were better than expected, they do not tell me that underlying trends have meaningfully improved."

"Here is my standard: We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do. That's our job... our mandate... and our charge to keep."

In his words, Warsh says the Fed has "work to do."

The second leg is the most recent BLS jobs report. Nonfarm payrolls jumped 162,000 in August, more than triple the 50,000 number Wall Street expected. Furthermore, the prior negative 23,000 number was revised upward to a positive 21,000, and the unemployment rate held steady at a historical low of 4.1%.

For the prosecution, that exhibit fits well with New York Fed President John Williams's claim that rising bond yields simply "reflect the strength of the economy." Fed Governor Lisa Cook, a more dovish member, seems to be coming around to the idea of rate hikes, telling reporters, "I would support an increase if it becomes necessary to bring inflation down. It may not."

Beth Hammack- The Lead Prosector

Beth Hammack, President of the Cleveland Fed, has been the most consistently hawkish voice on the committee and presents the third leg- the persistence of high inflation. She dissented at the last FOMC meeting in favor of a hike, arguing that the Fed likely needs a sequence of rate increases rather than a single move, and has recently said that "now is the time to act."

Hammack doesn't seem concerned that higher interest rates will impede the economy. To wit,

One 25 basis point move probably doesn't do a whole lot for the economy

Her overarching reasoning is that current rates aren't restrictive; accordingly, they won't bring inflation back to 2%.

I just don't see it coming back on its own

Furthermore, she believes delaying rate hikes only makes the job harder later and that inflation is more broad-based than just oil.

Regarding the labor market, she has pushed back on weak-jobs narratives, saying she's "still not seeing a problem" and pointing to unemployment close to full employment.

The labor market is right around my level of maximum employment.

Her employment view helps explain why she's comfortable prioritizing fighting inflation over the health of the labor market. The most recent employment data will strengthen her opinion.

The Defense's Case: Hold Rates Steady

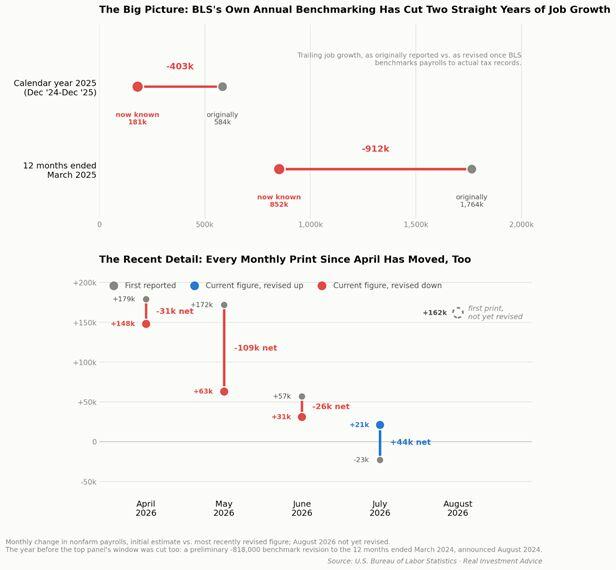
The defense will not put much faith in the recent employment report. Instead, it will focus on the recent string of weak employment data and, importantly, the large revisions that have turned good job reports into bad ones. That skepticism over jobs data is warranted, as shown in the chart below.

Twice a year, BLS benchmarks and revises the payroll survey against actual unemployment-insurance tax records. The preliminary 2025 benchmark knocked 911,000 jobs off the year ended March 2025, cutting average monthly growth in half from a reported 147,000 to 71,000. When it was finalized in January, calendar-year 2025 growth got cut again, from a reported 584,000 down to just 181,000. The year before that, the preliminary 2024 benchmark had already cut 818,000 jobs from the year ended March 2024.

More recently, April's initial 179,000 gain is now 148,000, and May's initial 172,000 gain is now just 63,000. July was reported as an outright loss of 23,000 jobs but has since been revised up to a positive 21,000. An economic data series that has been grossly overstated in two straight annual benchmarks and then turned a reported loss into a gain within a month is data that we must be dubious of. Last week's gain of 162,000 jobs has not yet been revised.

Richmond Fed President Tom Barkin's read on the underlying labor market is as follows: "It's not loose, it's not tight, it's sort of been a weak balance," he said, describing employers who are neither firing employees aggressively nor expanding their payrolls.

Inflation And Other Risks

On inflation, the defense will note that the July CPI report was benign. Headline CPI rose just 0.1% month-over-month, and core CPI rose 0.2%, but year-over-year rates of 3.4% headline and 2.5% core are above the Fed's 2% target. The recent trend, not the dated annual comparison, is what should matter most for a forward-looking rate decision, and the monthly trend is cooling.

It's worth adding that the Dallas Fed Trimmed Mean PCE, which ignores the most volatile components of PCE, sits at 2.28%, close to the Fed's 2% target. At his Senate confirmation, Warsh cited the trimmed mean as a valuable inflation gauge. Furthermore, five-year inflation expectations, another tool many Fed members rely on, sit at 2.4%, slightly below where they were before the Iranian conflict.

The defense's strongest proponent may be Governor Waller, who argues against rate hikes. He believes that the forces pushing yields higher are largely outside the Fed's price stability and full employment mandate. The forces include deficits, dollar concerns, AI-related capital needs, and the oil shock tied to shipping disruptions rather than domestic demand. Hiking to fight yield narratives risks a policy error.

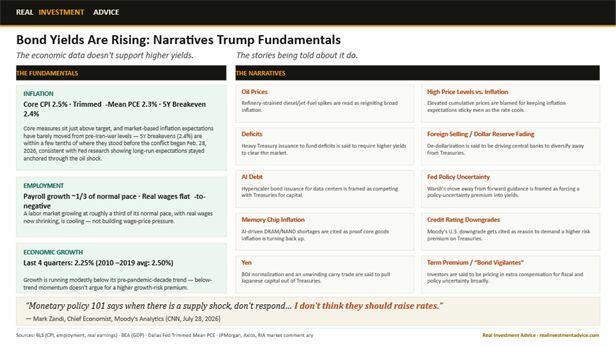
The table below shows the fundamentals and narratives impacting the Fed's decision.

The Evidence

To assess both sides, let's review recent trends in the Fed's two mandates: employment and prices.

Labor Markets

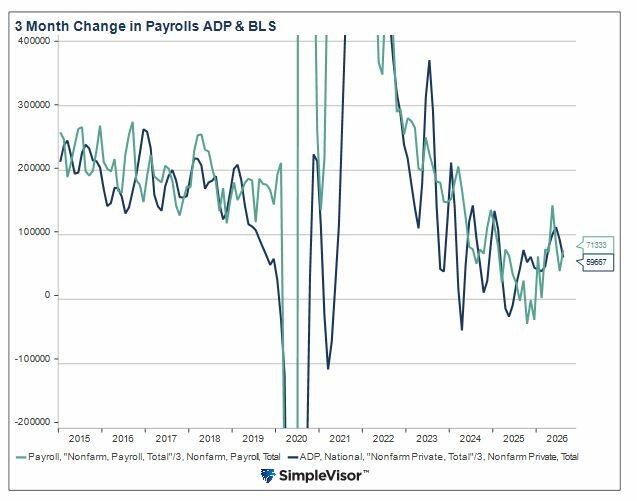
While the most recent labor data from the BLS was strong, we are highly skeptical, as negative revisions have plagued BLS data. Furthermore, recent ADP and JOLTS data offer little confirmation of a sharp pickup in hiring. The graph below showing the 3-month moving average of BLS and ADP highlights that 60k to 70k jobs are being added monthly, which is well below the 150k to 250k range preceding the pandemic. The labor force has grown by 8 million people since 2018, making recent data even worse in comparison.

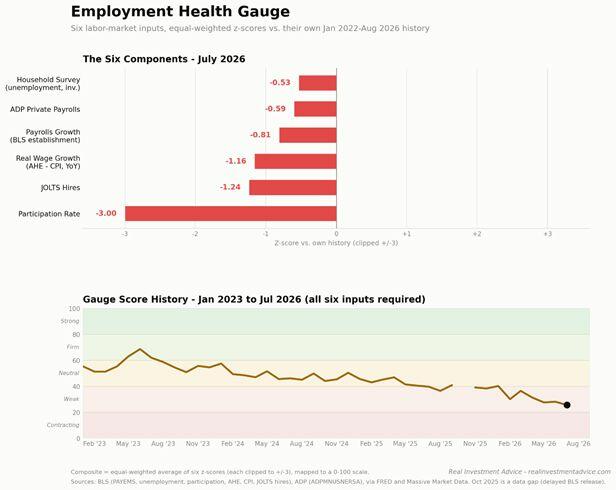
To better assess the labor market and its recent trend, we created a model using the following six factors:

  • BLS household employment - survey of individuals
  • BLS establishment employment - business survey and payroll records
  • BLS labor participation rate
  • ADP private payrolls
  • Real wage growth
  • JOLTS hires index

Our model expresses each of the six factors as a z-score against its own history since January 2022. This model doesn't provide a historical reading on employment but shows that the weakening trend of the last few years has worsened over the last six months.

Inflation

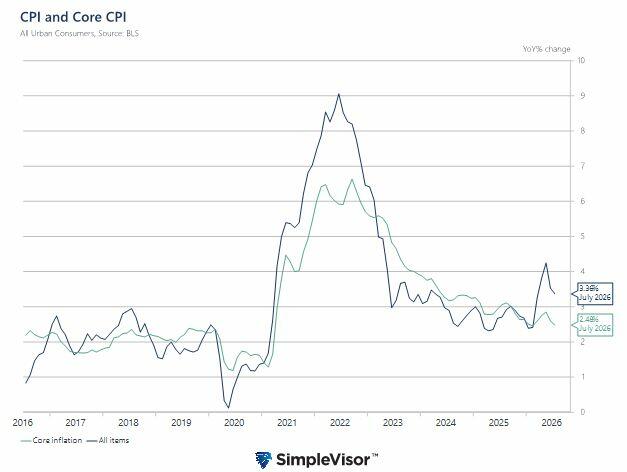
The graph below shows that year-over-year Core CPI sits near 2.5%, almost exactly where it stood before the Iranian conflict started. Moreover, the slow trend toward 2% still appears intact. That said, headline CPI remains elevated at 3.4%.

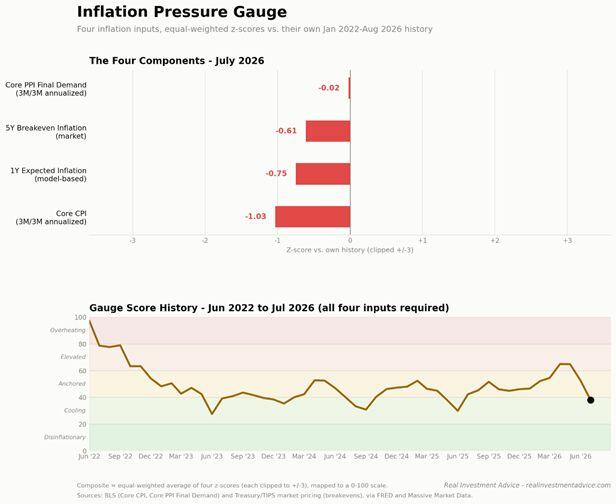
As we did with labor, we created an inflation trend model. This four-factor model compares the most recent three months of inflation data to the prior three months to detect trends.

Per the model shown below, inflation has been "anchored" since January 2023, albeit with a short spike coinciding with the Iranian conflict. Since then, the gauge has receded back toward 2025 levels and is now edging into the "cooling" zone. Like the employment gauge, all factors have a negative z-score, indicating the recent trend is softening.

Summary: Our Verdict

We are sympathetic to both sides. The prosecutor is 100% correct that we need to get inflation back to 2% as soon as possible. It has been above target for too long, and the Fed risks consumer and corporate spending behaviors changing in a pro-inflationary way. The debate at the Fed seems to come down to whether they let that occur naturally or force the issue.

The prosecuting side wants to raise rates to force inflation lower. The defense wants to wait, claiming the disinflationary trends that existed before the Iranian conflict are reasserting themselves and that higher rates could worsen an already weak labor market.

Some Fed members, including Warsh, claim that the recent spike in yields across the yield curve makes borrowing more restrictive for consumers and corporations, effectively doing the job for them.

We come down on the side of the defense, though the August employment number, assuming it holds up through revisions and similar strength persists, does weaken our case. Inflation should be hotly debated as it is. We are comfortable with recent trends and somewhat comfortable that, assuming oil prices don't spike, price trends continue lower.

The credibility argument supporting a rate hike concerns us most. The idea is that the Fed needs to raise rates to address rising bond yields and reassert "credibility," rather than respond to a confirmed breakdown in either of the Fed's dual mandates.

Yields have risen largely because of an oil-driven supply shock and concerns about swelling fiscal deficits. The Fed's short-term policy rate is poorly suited to address them.

Tyler Durden Thu, 09/10/2026 - 07:45

Brent Tops $102 As Mideast Conflict Intensifies, HSBC Hikes Oil Forecast

Brent Tops $102 As Mideast Conflict Intensifies, HSBC Hikes Oil Forecast

Brent crude futures traded above $102 a barrel Thursday morning after Iran threatened to intensify attacks, renewing concerns over tanker flows through the Hormuz maritime chokepoint. The supply risk extends well beyond crude to mounting shortages of refined products, particularly diesel, as the US diesel crack spread trades around $102 a barrel.

President Trump's indication yesterday that the conflict could continue beyond November's midterm elections suggests limited near-term fuel pump relief for working-class folks, with the US national gasoline average above the politically sensitive $4-a-gallon threshold and diesel at a record high. Trump also announced overnight a proposal for a $5,000 "Trump dividend" check for every American adult if Republicans retain control of both chambers of Congress.

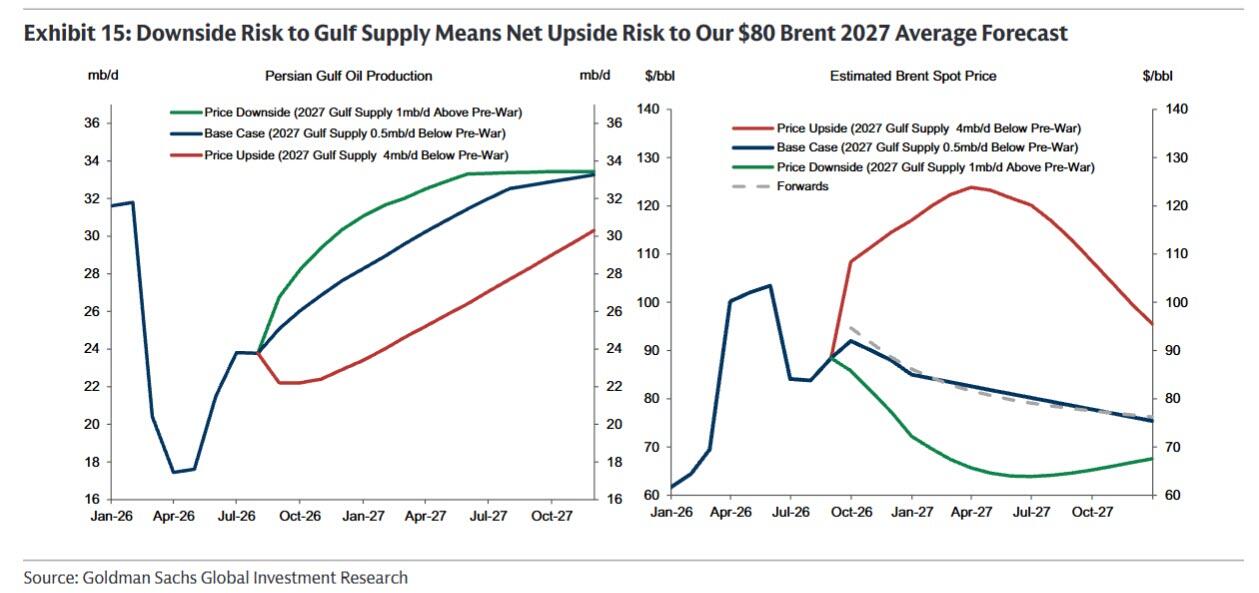
Following Goldman, HSBC raised its 2026 average Brent crude forecast to $90 a barrel from $80, citing continued disruptions to shipping through the critical Gulf waterway that are expected to keep global oil balances tighter for longer.

With Hormuz flows running at roughly 30% of pre-conflict levels, HSBC analysts see the market adjusting to a prolonged period of depressed tanker transit through the chokepoint. That outlook suggests sustained supply constraints through year-end.

"The key indicator to watch is whether this will put an end to the heavy shuttling of oil through the Strait of Hormuz," said Arne Lohmann Rasmussen, chief analyst at Global Risk Management in Copenhagen. "It may not come to a complete halt, but combined with the more aggressive Houthis in the Red Sea and higher Chinese crude oil imports, the global oil market balance appears to be deteriorating again."

Earlier this week, Vitol Group CEO Russell Hardy said about 10 million barrels a day have been crossing the waterway, roughly half of pre-war levels. He added that an exact figure is hard to quantify and that volumes aren't guaranteed daily.

Read:

Goldman commodities strategist Yulia Zhestkova Grigsby sharply revised tanker-flow estimates through the Hormuz chokepoint to between 15 million and 16 million barrels per day, roughly two-thirds of pre-war levels. That's mainly because the market is not counting ships that turn off their automatic identification systems to avoid detection by Iran.

Goldman's Daan Struyven also noted one upside scenario this week that could push Brent to $120 if the conflict persists...

"The fundamental picture for products remains bullish with global inventories and reserves deteriorating," said Darrell Fletcher, managing director for commodities at Bannockburn Capital Markets. Before 'Operation Epic Furry', about a fifth of the world's oil and liquefied natural gas passed through Hormuz to global customers, mainly in Asia. The ongoing disruptions have sent NatGas prices in Europe above 81 euros on Thursday. 

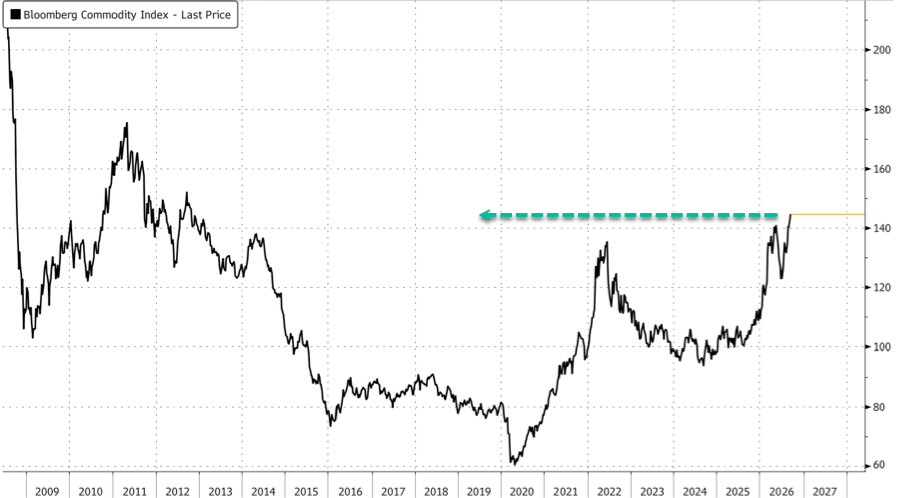
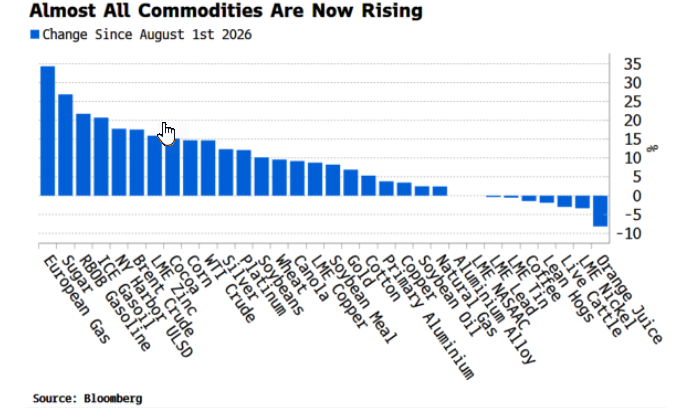
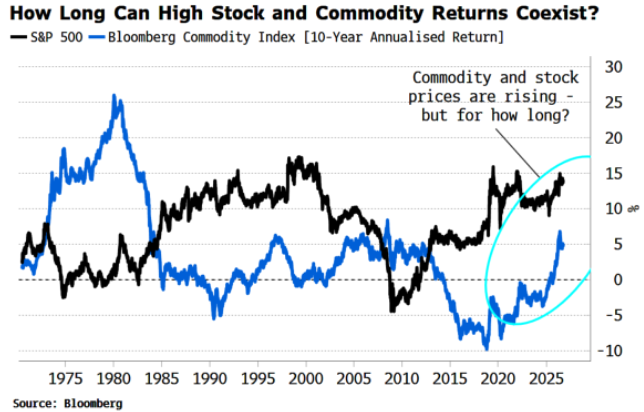
Beyond energy, a broad-based commodity rally has pushed agricultural products and metals higher, sending the Bloomberg Commodity Index to levels last seen in 2012. HSBC analysts spot a commodities cycle developing into a "super squeeze," which suggests the move could be sustained.

Tyler Durden Thu, 09/10/2026 - 07:20

HSBC Sees "Upside Risks" From "Super Squeeze" In Commodities

HSBC Sees "Upside Risks" From "Super Squeeze" In Commodities

London copper futures are trading north of $14,700 a ton, Brent crude futures have climbed above $101 a barrel, US diesel crack spreads are back in triple-digit territory, and the Bloomberg Commodity Index is at a 14-year high. The energy shock has broadened into a rally across the commodity complex, from energy to agricultural products to metals and other critical materials, with a growing number of Wall Street research desks identifying tightening physical supplies as a key driver.

HSBC chief economist for global commodities Paul Bloxham is the latest to warn that a "super-squeeze" in commodity markets continues to produce outsized gains.

"The 'super-squeeze' has continued to support elevated commodity prices … as the Iran and Russia-Ukraine wars and El Niño disrupt supplies … and AI and electrification drive demand," Bloxham wrote at the start of the note. "Prices are expected to remain elevated, and there are upside risks."

To illustrate the broad-based surge in commodity prices, the Bloomberg Commodity Index is now at levels last seen in 2012, marking a 14-year high...

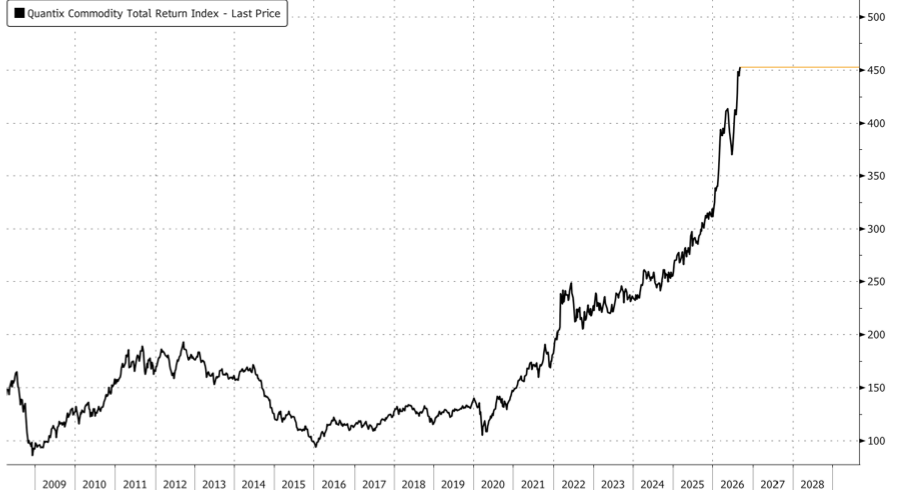
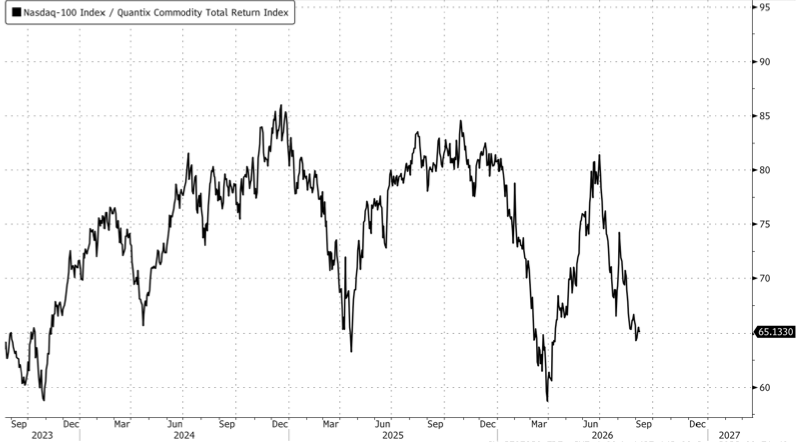
... while the Quantix Commodity Index has hit a new record high.

Bloxham told clients to focus on these ten themes:

1) A'super-squeeze' continues …

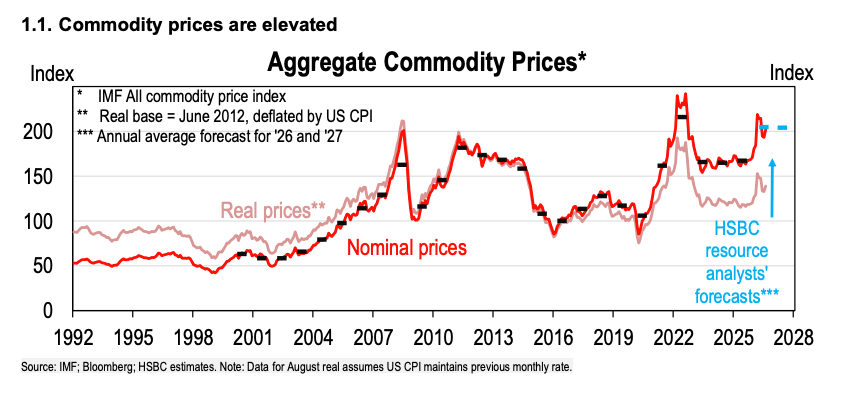
Six months after the Middle East conflict began, it is still a key driver of commodity prices. Commodity prices are well above the pre-Iran war levels, despite being below the peaks reached early in the conflict. The worst-case possibilities have, so far, been avoided, largely because of rapid drawdown of inventories, but the global commodity price index is up 18% YTD and 24% y-o-y in August. The team's base case sees an average rise of 22% in 2026 (16% prior) and flat in 2027 (-7% prior), leaving our 2027 forecast 14% higher than previously expected. 

We see risks to these forecasts being to the upside as the 'super-squeeze' continues.

2) … with disruption from the Iran and Russia-Ukraine wars …

The Middle East conflict remains the key risk. The Strait of Hormuz remains largely closed, with significant uncertainties about when it will open and on what terms. A cycle of escalation and de-escalation of the conflict has been repeated many times in recent months, driving volatility. The Middle East conflict has also broadened, with attacks by the Houthis on Saudi ships in the Red Sea disrupting traffic though the Bab el-Mandeb Strait too. In addition, the Russia-Ukraine war, which is now in its fifth year, has been a more acutely disruptive force recently, including for supplies of grains and refined oil products, like diesel.

3) … and a strong El Niño weather event

Extreme weather is another upside risk to prices. A strong El Niño has arrived, with the Southern Oscillation Index already at extremes not reached in over two decades. This is a particular risk for agricultural supply, where the Middle East conflict has already disrupted fertiliser and diesel supplies and the Russia-Ukraine war has disrupted shipping. A recent Northern Hemisphere heatwave has also shifted patterns in energy consumption with implications for stocks of key energy commodities. El Niño is also affecting manufacturing supply chains, and thereby impacting commodity markets. 

4) Inventory rundown in focus, particularly for oil and gas

High inventories and rapid drawdown of these inventories - particularly of oil and gas - has been a key factor helping to, so far, balance markets in the face of the 'super-squeeze'. In the oil market, the US has been exporting more - as it runs down its strategic reserves - and China has been importing much less - as it too runs down reserves. However, the longer the disruptions continue, the greater the upside risk to prices, as stocks fall to levels that start to approach 'tank bottom'. For gas, European inventories are well below target, reflecting a very hot summer, with lower stocks increasing the risk of high prices in the coming winter.

5) More than just oil - sulphur, diesel and jet fuel disrupted too

The supply disruptions, particularly due to the Middle East conflict, extend well beyond oil and gas. In particular, there have been significant disruptions to supplies of sulphur, fertiliser, aluminium and helium -- as well as a range of refined oil byproducts, such as jet fuel, naphtha and diesel. The Russia-Ukraine war has more acutely affected supplies of products such as diesel, as the conflict has led to recent significant damage to refining capacity.

6) Metals and energy prices supported by AI and electrification

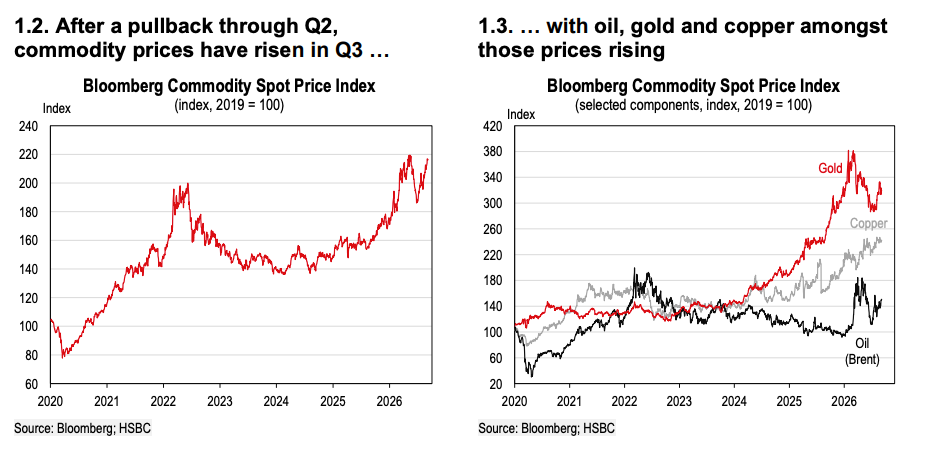
Most base metal prices have risen recently, as the boom in AI infrastructure investment and the energy transition have supported electrification demand. Copper prices have increased to all-time highs, partly reflecting strong demand, but also limited investment in new mines constraining supply and supply disruptions. For aluminium, although the Middle East conflict has been disruptive, China dominates global supply and some cargoes have cleared the Strait of Hormuz, containing the upside to prices. Lithium prices have also risen strongly over the past year, up 130%, but as with previous cycles, this has triggered more supply, particularly from Zimbabwe and Australia, which could curb the price upside.

7) China's slowdown weighs on bulk commodities

Despite good support for base metals from the AI and electrification booms, falling fixed asset investment in China, particularly the ongoing property correction, which is now in its fifth year, has weighed on demand for iron ore, coking coal and steel. That being said, this year China's authorities announced more infrastructure investment plans, worth around RMB7 trillion, as part of the 'Six Networks' initiative, which should support demand for bulk commodities and their prices. For iron ore, on the supply side, there have been large changes to pricing as the China Mineral Resources Group (CMRG) centralised Chinese buying and the ramp-up in production from the Simandou mine in Guinea adds in more supply.

8) Grains and 'finer foods' prices rise, as supply squeezed

Agricultural markets have been heavily affected by the disruptive impacts of the Middle East and Russia-Ukraine wars, particularly to supplies of fertilisers and diesel. The El Niño event, Northern hemisphere heatwave and record high ocean temperatures (a positive Indian dipole) are all risks to the outlook for supplies. An El Niño event creates more volatility in agricultural prices, by disrupting supply. Winners are typically North and South America, with much of Asia typically worse off, with higher drought risk in Australia and Indonesia, a weaker monsoon in India and hotter and drier conditions in South-East Asia. Grains prices have been rising recently, led by wheat, and 'finer foods' prices are rising too - particularly cocoa and coffee.

9) Precious metal prices are high and we see more upside

After a significant rise in precious metals prices through 2025 - gold prices more than doubled to their peak in January 2026 - prices have edged lower across the precious metals complex year-to-date in 2026. A key driver has been a rise in interest rates - particularly at the long-end of yield curves - which has encouraged investors to seek yield and thus move away from precious metals. That being said, with geopolitical risk still high, central bank demand still positive, and more uncertainty in bond markets, precious metals prices are well supported. Platinum and palladium prices may also be supported by constrained mine supply.

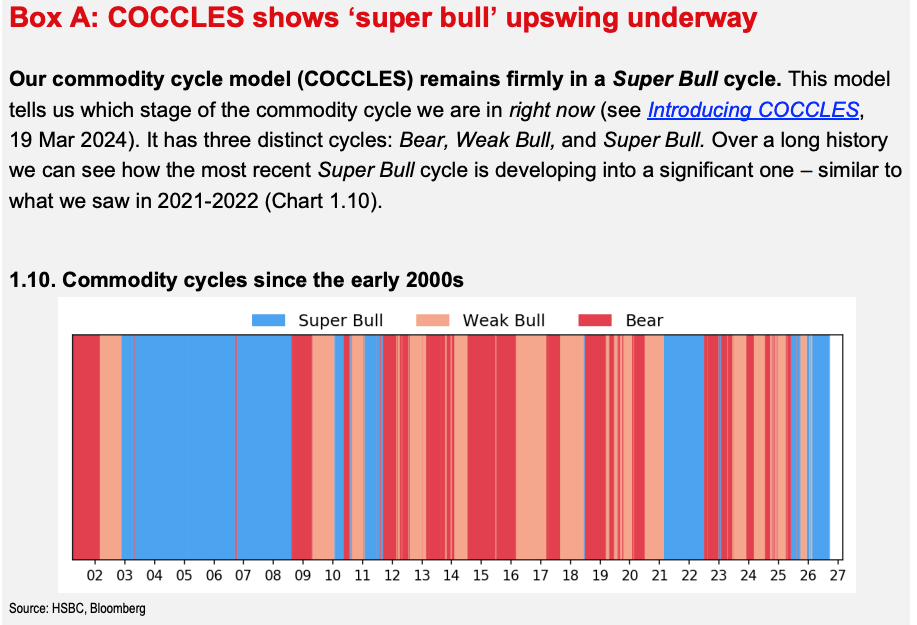
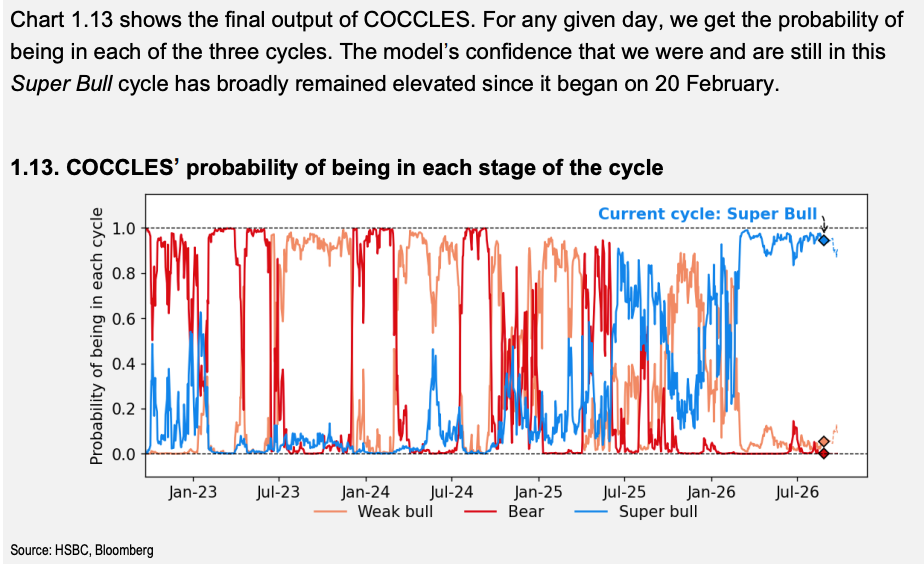
10) COCCLES suggests a 'super-bull' phase underway

Finally, HSBC's purely statistical model, COCCLES, which looks for patterns in commodity prices, shows that the market is convincingly in a 'super-bull' phase of the cycle.

This model is not structural, but it does tend to be the case that once a super-bull phase begins, it tends to persist much longer than the other phases do. 

This model result lends statistical support to the view that commodity prices will remain elevated. 

With HSBC's commodity-cycle model firmly signaling a "super-bull" phase, the big question for traders now is how long physical scarcity themes and other supply constraints can collide with demand to sustain the rally. 

Tyler Durden Thu, 09/10/2026 - 06:55

US-Saudi Nuclear Deal Clears Vienna Hurdle As Congress Review Continues

US-Saudi Nuclear Deal Clears Vienna Hurdle As Congress Review Continues

Authored by Michael Kern via OilPrice.com,

  • IAEA chief Rafael Grossi says Saudi Arabia won't sign the Additional Protocol but will accept oversight powers over enrichment, conversion and reprocessing that closely mirror it.

  • The underlying US-Saudi 123 agreement, signed July 22, opens a path to domestic uranium enrichment after a two-year study, a break from the UAE's enrichment-free 'gold standard.'

  • Congress is 90 days into reviewing the deal, with Democrats and nonproliferation groups pushing back and two side letters still classified.

A planned nuclear cooperation deal between the United States and Saudi Arabia won't include the toughest inspection regime the U.N.'s atomic watchdog has to offer, but it's going to come close on the activities that matter most.

That's the picture International Atomic Energy Agency chief Rafael Grossi laid out Monday in Vienna, speaking to reporters during the agency's September Board of Governors meeting. Riyadh isn't signing the IAEA's Additional Protocol, the tool that lets inspectors show up unannounced at sites a country hasn't even declared. But Grossi said Saudi Arabia is preparing to grant the agency verification and monitoring authority over its most sensitive nuclear activities, uranium enrichment, the conversion step that precedes it, and reprocessing, that functions almost the same way.

"These are sensitive activities, as we all know," Grossi told reporters. The new powers being built into the bilateral safeguards agreement, he said, will be "very, very similar" to what the Additional Protocol provides, though he declined to spell out specifics. Once finished, that safeguards agreement still has to go before the IAEA's own 35-member Board of Governors for sign-off.

A Deal Years In The Making

The framework goes back to a 123 agreement that Energy Secretary Chris Wright and Saudi Energy Minister Prince Abdulaziz bin Salman signed on July 22, capping more than a decade of on-and-off talks that repeatedly stalled over Riyadh's refusal to give up enrichment as a condition of U.S. cooperation. The pact, named for the section of the Atomic Energy Act that governs U.S. nuclear exports, opens the door for American firms to build reactors in the kingdom and hands Riyadh something it has wanted for years: a real shot at enriching its own uranium.

Under the terms reported at signing, Washington and Riyadh have two years to study whether domestic enrichment makes commercial sense. Any enrichment plant built afterward would go up under a "black box" model, run by U.S. companies inside Saudi Arabia so the underlying technology never actually changes hands. It's a sharp departure from Washington's 2009 pact with the United Arab Emirates, the deal nonproliferation advocates still call the gold standard, under which Abu Dhabi permanently gave up enrichment and reprocessing altogether.

Congress Gets Its Say

The administration sent the agreement to Congress in late August, starting a 90-day review clock under the Atomic Energy Act. Lawmakers can let it take effect by doing nothing, or pass a joint resolution of disapproval to kill it, though that would need to survive a presidential veto. Two side letters attached to the deal remain classified, according to the Foundation for Defense of Democracies, which also notes that of the 51 countries with active 123 agreements, only Argentina and Brazil currently lack the Additional Protocol. Saudi Arabia would be the third.

Congressional Democrats have pushed back hard, joined by some Republicans, arguing the deal opens the door to a wider enrichment race across the Middle East. The White House, meanwhile, has tied the agreement to Saudi Arabia eventually joining the Abraham Accords and normalizing relations with Israel, a step Riyadh has so far declined to take without progress toward Palestinian statehood.

The Backdrop

For Riyadh, the deal is also part of a broader push under Vision 2030 to build out nuclear power alongside renewables and diversify an economy still tied to oil exports, with U.S. firms like Westinghouse positioned to compete for reactor contracts worth billions. The talks are unfolding against last year's war between Israel and Iran, which has hardened Gulf calculations around nuclear deterrence. Crown Prince Mohammed bin Salman has said publicly the kingdom would pursue a weapon of its own if Iran ever built one. Iran, for its part, operated under the Additional Protocol from 2016 to 2021 under the nuclear deal that collapsed after the U.S. withdrew in 2018, a history nonproliferation groups keep pointing to as they push for tougher terms on Riyadh.

For now, the deal sits in a kind of holding pattern. Congress's review runs deep into the fall. The bilateral safeguards text is still being finalized in Vienna. And whether the arrangement Grossi described Monday ends up satisfying skeptics on Capitol Hill, or just gives them a new set of details to pick apart, is still an open question.

Tyler Durden Thu, 09/10/2026 - 06:30

Migrants Responsible For 47% Of All Violent Crime In German State Of Bavaria

Migrants Responsible For 47% Of All Violent Crime In German State Of Bavaria

Via Remix News,

Non-German suspects account for nearly half of all violent crime in the German state of Bavaria, with the anti-immigration Alternative for Germany (AfD) party now calling for remigration for all criminal migrant suspects. The Interior Ministry data was released in response to a request from AfD state parliament member Martin Böhm. It revealed that police recorded 20,367 suspects in violent offenses in 2025 and about 47 percent did not have German citizenship.

Remarkably, foreigners are responsible for this massive amount of serious crime despite making up only 15.5 percent of Bavaria's population.

Syrians were the largest group of non-German suspects, at 1,284, followed by Turks with 799, Ukrainians with 797, Afghans with 784, Romanians with 687, Iraqis with 428, Bulgarians with 350, Poles with 328, Kosovars with 319, and Italians with 250.

A different ranking appears when the figures are adjusted for population. The suspect burden figure, or TVBZ, measures how many suspects police identified per 100,000 people in a group over one year.

Ukrainians had the highest TVBZ, at 555. Turks followed at 445 and Romanians at 435. The figure for German citizens was 106. That means Ukrainians, for instance, are more than five times more likely to commit a violent crime than Germans.

The government did not calculate a TVBZ for other nationalities because each had fewer than 100,000 residents.

"For smaller population groups, the crime rate would have to be mathematically extrapolated to 100,000 people," the state government wrote.

"However, since the relationship between population size and crime burden is not strictly linear, an error would occur in the TVBZ calculation, which is greater the smaller the population group. For this reason, the TVBZ are only calculated for non-German citizens who have a population share of over 100,000 people."

When it comes to murder and manslaughter, there were 411 suspects in Bavaria and 177 were non-Germans, equaling 43.1 percent of all murder and manslaughter suspects. The TVBZ for Germans was 87, while Turks had a TVBZ of 478 and Ukrainians with a TVBZ of 499.

In cases of rape, sexual assault and sexual assault in particularly serious cases, including those resulting in death, police registered 1,288 suspects in Bavaria. Of those, 551 were foreigners, equaling 42.8 percent.

It must also be noted that for all German suspects counted in this data, the Interior Ministry does not release if they have a foreign background.

Böhm said the figures show that violent crime in Bavaria is an imported problem to a "far too high" extent.

"No amount of sugarcoating or trivialization will help. The numbers speak for themselves," he told Junge Freiheit, which exclusively received the figures.

"The AfD therefore demands: decisive action by the judiciary, an end to mass naturalizations and rigorous remigration of foreign violent criminals," Böhm said.

Read more here...

Tyler Durden Thu, 09/10/2026 - 05:00

America's Next Military Contractors Could Be Hackers

America's Next Military Contractors Could Be Hackers

Washington may soon outsource part of its cyberwarfare operations to private companies, according to a new report from Bloomberg

Language tucked into the Senate’s 2027 defense bill would create a pilot program allowing the Pentagon to hire outside cybersecurity firms to penetrate computer networks chosen by the US military. Contractors would operate under US Cyber Command and Pentagon supervision.

Bloomberg writes that the authority would initially be relatively narrow. Private operators could establish access to targeted networks, but the Senate language stops short of authorizing them to damage, disable or destroy those systems.

Still, it would represent a significant expansion of private industry’s role in US offensive cyber operations. The administration has already moved in this direction, launching a separate initiative that permits American companies to pursue certain foreign cybercriminal groups under federal oversight.

Advocates say outsourcing some of the work could provide badly needed manpower and expertise as Cyber Command faces growing demands and staffing pressures. Opponents argue that introducing profit-driven companies into cyberwarfare could create new problems, including retaliation, accidental escalation and murky accountability.

If enacted, the experiment would start in 2027 and continue through 2030, with the Pentagon required to regularly disclose information about contractors, missions and targets to Congress.

For now, however, it remains only a Senate proposal. The House defense bill contains no equivalent measure, meaning the provision could still be changed or removed before reaching the president.

Tyler Durden Thu, 09/10/2026 - 04:15

"Really Bright Future": Wall Street's Big Bet on Booming Red America Escalates

"Really Bright Future": Wall Street's Big Bet on Booming Red America Escalates

Goldman Sachs is nearing a major milestone on its new Dallas campus, where the exterior of an 800,000-square-foot building is nearly complete and the Wall Street firm is preparing to begin work on the interior ahead of a planned January 2028 opening.

The new Goldman Sachs campus in downtown Dallas is under construction, with a projected opening in January 2028. (Shelby Tauber via Getty Images, yoinked from Fox News)
The project will consolidate two existing Goldman offices into a single campus and give the firm more room to expand in a city that is already its second-largest U.S. base after New York, with roughly 4,500 employees across North Texas. The roughly $500 million campus is designed for more than 5,000 workers and will be the largest office by square footage in Goldman's portfolio when it opens - larger than anything the firm occupies in Manhattan. Ericka Leslie, Goldman's chief administrative officer, recently inspected the site and said Dallas has so far lived up to the firm's expectations.

"I can't say it enough, I think Dallas is a great place to do business, it really is. The building is beautiful," Leslie told Fox Business.

"We're in two buildings now, we're going to be able to combine everybody into this state-of-the-art space, and it's right next to the Perot museum, and the city itself is very vibrant. So we're looking forward to it, and we're going to grow there," the Wall Street executive continued. "It's a growth opportunity for us inside of the United States, and it's a really vibrant place to do business."

"The outside of the building is mostly complete, and they have to do that in order to start fitting out the inside of the building and air conditioning it, so that will begin fairly shortly. We're looking for a launch around January 2028," she added.

The new campus will offer views overlooking downtown Dallas and the Perot Museum, including from outdoor areas. (Goldman Sachs)
However, January 2028 is running a little late versus Goldman's original plan. Dallas is so busy building that even Goldman has to wait in line for contractors.

"The project is mostly on time. It's slightly delayed, there's quite a bit of development going on in Dallas right now, and so we're seeing small delays," she said.

The math behind the move is straightforward. CEO David Solomon has noted that Goldman's headcount in New York has not grown in 20 years, while Dallas and Salt Lake City are where the firm is adding people.

Goldman is hardly alone in putting more people and money into Texas. Some of the biggest names in finance are expanding their presence in the state, adding offices and employees as Texas seeks to establish itself as a larger rival to traditional financial centers on the East Coast.

For example, Morgan Stanley is planning a permanent Dallas hub by 2031. Under a July 2026 resolution filed with the Dallas City Council, the firm plans to spend just over $587 million on a 708,000-square-foot building expected to house about 3,800 employees by the end of 2035. At least 25% of relocated or newly created positions are required to go to Dallas residents. That works out to roughly $829 per square foot, against about $625 for Goldman's campus.

The new Goldman Sachs campus in Dallas will allow the firm to consolidate and grow its presence in the region. (Goldman Sachs)
Texas is also making a push into the infrastructure of financial markets themselves. The Texas Stock Exchange, backed by BlackRock, Citadel Securities, Charles Schwab and Goldman itself, raised $161 million, making it the most well-capitalized exchange applicant in U.S. history. The exchange went fully live in late July.

Meanwhile, Apollo Global Management is expanding farther south in Austin, which the firm selected for a new hub focused on innovation, emerging technology and its next phase of growth.

"At Apollo and Athene, we help meet the capital needs of companies and economies, while enabling people to retire with confidence. That mission has driven our innovation for more than three decades, and this new presence is a continuation of that DNA. Change is the only constant, and we'd rather lead it than react to it," Apollo CEO Marc Rowan said. "Austin lets us build the next generation of Apollo and Athene, including challenger models for parts of our own business, with the talent, technology and business environment already in place. That's why we chose Austin and Texas."

Tyler Durden Wed, 09/09/2026 - 20:30

University Of Washington Settles Case Against Professor Disciplined For Mocking Land Acknowledgment

University Of Washington Settles Case Against Professor Disciplined For Mocking Land Acknowledgment

Authored by Jonathan Turley via JonathanTurley.org,

Land acknowledgments have become standard at academic and political events, including the opening of the Obama Presidential Library and a recent Michigan Democratic event. While supporters insist it merely shows respect for original inhabitants, critics argue it is the ultimate virtue signaling and is increasingly being forced on both speakers and audiences. One critic is Professor Stuart Reges, who teaches at the computer science and engineering school of the University of Washington. He has now received a settlement from the University of Washington, which spent a significant amount of time and resources in response to his mocking of the school's land acknowledgment.

University of Washington

We previously discussed the case of Professor Reges, who was disciplined because he refused to post the school's "land acknowledgment" and instead posted an alternative statement. Professor Reges sued the university and various officials in 2022. Professor Reges has declared "Land acknowledgments are performative acts of conformity that should be resisted, even if it lands you in court."

The defendants included Nancy Allbritton, the Dean of the College of Engineering at the University of Washington, Magdalena Balazinska, Director of the Allen School, UW President Ana Mari Cauce, and the Allen School's Vice Director Dan Grossman.

After the university encouraged faculty to add a prewritten "Indigenous land acknowledgment" statement to their syllabi, Reges decided to write his own statement. He has now been told that, while the university statement is optional, his statement is unacceptable because it questions the indigenous land claim of the Coast Salish people.

The school provided a recommended statement for all faculty to post and/or read to their students at the first of every course:

"The University of Washington acknowledges the Coast Salish peoples of this land, the land which touches the shared waters of all tribes and bands within the Suquamish, Tulalip and Muckleshoot nations."

Professor Reges disagreed with that statement and expressed his doubts to the faculty while also noting that "Magda" did not want the faculty to discuss such reservations on the email system. That may refer to the Director of the Paul G. Allen School of Computer Science & Engineering, Magdalena Balazinska.

Reges' alternative statement read:

"I acknowledge that by the labor theory of property the Coast Salish people can claim historical ownership of almost none of the land currently occupied by the University of Washington."

The labor theory (which I teach) generally refers to John Locke's theory. In his Second Treatise, Locke laid the foundation for property as a divine gift of God that began in the state of nature, where all was created in common by God. Reges declared that these tribes, indigenous people, "can claim historical ownership of almost none of the land and that the claim of the university land was not sufficiently used or developed to bestow a claim upon the Coast Salish people. That acknowledged group is a broad collection of different groups with ethnic or linguistic associations."

In his lawsuit, Professor Reges says that, after he stated his own views, the university moved against him.

"On January 4, 2022, the day after Professor Reges's Computer Science and Engineering 143 class met for the first time, Defendant [Magdalena] Balazinska, Director of the Allen School, sent Professor Reges an email ordering him to remove the statement from his syllabus because it was 'offensive' and created a 'toxic environment.'"

Reges noted that the university allowed other professors "to include modified statements in their syllabi that were more consistent with the University's recommended statement." The operative point is that "other faculty at the Allen School continue to include land acknowledgment statements in their syllabi that differ from the University's own statement, so long as they express a viewpoint consistent with the University's recommended version."

According to the complaint, Balazinska then allegedly removed his dissenting statement, and the university emailed his students to apologize for their professor's "offensive" land acknowledgment opinion and advised them on "three ways students could file complaints against" him. The students were later allegedly told by Balazinska that, according to the complaint, "all students in Professor Reges's Computer Science and Engineering 143 class section [can] switch into a new 'shadow' class section, which would meet at the same time as Professor Reges's class section."

Reges notes that the alternative class was a series of recorded lectures, but viewed as a reasonable alternative to being in a class with a professor with a dissenting view on land acknowledgments. Some 170 out of his 500 students took the alternative course.

I previously wrote how universities can use course assignments and other collateral means to isolate dissenting professors in an effort to get them to resign. This is especially true of tenured faculty.

I wrote that:

The Reges case could prove a major challenge to that orthodoxy. All university faculty should have condemned the university's actions as an attack on academic freedom and freedom of speech, regardless of how they feel about land acknowledgment. The silence, however, is a reflection of how much has changed in higher education."

It has now resulted in a $600,000 settlement after the university spent massive amounts of public money over four years to fight this lawsuit over the abusive treatment of Professor Reges.

The university settled only after the United States Court of Appeals for the Ninth Circuit ruled in December that administrators were "liable under the First Amendment for retaliation and viewpoint discrimination."

Unfortunately, there is no indication that the university officials who created this fiasco will be held accountable in any way. Millions were spent, and years of litigation were triggered by the orthodoxy of the university. However, these officials will likely be heralded by their colleagues, and nothing is likely to change in the University of Washington's intellectual echo chamber.

However, according to FIRE, the settlement "stipulates that the university cannot take any further action against Reges."

Congratulations to Professor Reges and FIRE for a well-fought case with potentially lasting implications in protecting free speech and academic freedom.

Tyler Durden Wed, 09/09/2026 - 20:05

Appeals Court Blocks IRS From Sharing Data With Immigration Authorities

Appeals Court Blocks IRS From Sharing Data With Immigration Authorities

Authored by Zachary Stieber via The Epoch Times,

The IRS may not disclose the addresses of illegal immigrants to immigration officials, a U.S. appeals court said on Sept. 8.

A three-judge panel of the U.S. Court of Appeals for the District of Columbia Circuit upheld a February ruling from a district court that deemed an IRS policy to share the addresses of tens of thousands of people with Immigration and Customs Enforcement (ICE) illegal in part because the policy failed to meet requirements in the law.

The unanimous panel agreed, rejecting arguments from the government to the contrary.

The policy "indisputably contravenes the requirements of section 6103," a law that governs when the IRS can share taxpayer information, Circuit Judge Cornelia Pillard wrote for the panel.

The law allows the IRS to disclose certain tax return information to other federal agencies for use in criminal investigations. To make a request, the head of the agency needs to identify the taxpayer by name and address, specify the relevant tax period, and explain why the information may be relevant to the probe.

Under a memorandum of understanding signed in April 2025 between the IRS and ICE, the latter asked for the last known address for more than 1 million people believed to be illegally present in the United States. ICE did not provide an address for some of the people on the list. Under the agreement, IRS workers sent 47,289 records to ICE before the district court stayed the process.

IRS officials requested the appeals court overturn the ruling. Government lawyers said that the groups that sued did not have standing, that the IRS did not have to follow procedures in the Administrative Procedure Act because the agreement was not a final agency action, and that the practice did not violate federal law.

Pillard wrote that at least one of the plaintiff organizations was sufficiently injured by the policy that it could bring suit, that the IRS did have to follow the procedures because the policy was a final action, and that the action violated federal law because ICE in some cases did not supply an address, as required by the law.

The law provides that the IRS can disclose information about a taxpayer to officials "personally and directly engaged" in criminal proceedings or investigations concerning that taxpayer, allowing disclosure as long as the field for the ICE point of contact is filled in, even if it said "unknown" or "to be determined."

ICE ended up putting the same person as the point of contact for each of the 1.28 million listed taxpayers for whom it requested information.

The judicial panel found that the government's practice "entirely fails to ensure that ICE lists a federal employee, let alone one 'personally and directly engaged' in a qualifying investigation of a particular taxpayer."

"Today's order is a resounding victory for the protection of all taxpayers' right to the confidentiality of their tax information in the hands of the IRS," Nina Olson, executive director of the Center for Taxpayer Rights, one of the groups that sued over the policy, said in a statement.

A spokesperson for the Department of Homeland Security, ICE's parent agency, told The Epoch Times in an email that the agency disagreed with the ruling.

"We will continue using every lawful tool available to locate and remove illegal aliens with final orders of removal, and this ruling in no way prevents us from doing so," the spokesperson said.

Tyler Durden Wed, 09/09/2026 - 19:15

Japan Is Telling You To Run To Gold

Japan Is Telling You To Run To Gold

Authored by Matthew Piepenburg via Von Greyerz,

Below, we look at lessons from Japan and its latest signals to prepare for a market sell-off, a debasement acceleration and a golden endgame.

Pattern Recognition

My father taught me long ago that the years teach things the days do not always notice.

In all areas of our lives, we slowly acquire perspectives earned by experience over theory and by time rather than guesses.

This is equally true of lives spent investing in markets and cycles. A certain pattern recognition is acquired that not even a Bloomberg terminal or AI robot can teach.

As one, for example, who traded through a dot.com bubble led by the undeniably transformative technology of the internet of all things, I remember well how everyone from Wall Street experts to Hollywood movies made it clear that names like Cisco, Yahoo and AOL were kings who would never be dethroned.

That felt very exciting.

At least until the NASDAQ lost 78% and two of those "kings" were carried off the market on their shields, while Cisco, which at least survived the carnage, would never be the same again.

Those days and years are now teaching us yet another lesson, one whose pattern few wish to see, for the simple reason that many are not, or never were, paying attention.

And as for such patterns or lessons, what very few are seeing today is that Japan's JGB, yen and Nikkei have just given us a familiar road map for what lies ahead for America's Fed, dollar and S&P.

I Think We're Turning Japanese (Yes, I Really Think So)

What is happening this year in Japan goes well beyond the otherwise significant conversations on the Japanese "Carry Trade."

As bond jocks constantly remind us of boring things like sovereign debt yields, it can often be too boring (or too scary) to confront.

Like the sun, topics like death and bond markets are often hard to look at directly.

The fact, for example, that the yield on the Japanese 30Y JGB just hit over 4.18% for the first time in its history may seem like a yawn to many otherwise doom-scrolling through the latest war, AI meme or DC scandal de jour.

But this historical yield spike out of Tokyo is far more than just another bond signal - it's a harbinger of things to come in your own backyard (and wallet).

The Canary in a Coal Mine

Much like the USA, today's Japan (which is the world's 3rd largest economy) is a paper tiger built on extraordinary debt (greater than 200% of its total economy) and a bond and hence stock market entirely supported by (and correlated to) a central bank fatally addicted to printing (debasing) trillions worth of its currency to keep its illusion of economic survival going.

If this profile looks a lot like America's and Europe's, that's because Japan is just a canary in the Western coal mine. Where it goes, we shall follow.

In fact, Japan's sins are in many ways our own, especially America's.

Blame It on the Experts

Just after the Nikkei literally died in 1989, a then-ambitious and much younger Ben Bernanke gave Tokyo a handbook to print their way out of collapse.

Bernanke would use a similar handbook when U.S. markets tanked years later in 2008. As we are now discovering, his expertise was anything but expert.

But during this period of mass MMT delusion and massive currency debasement, Wall Street was betting for years (decades) that Japan's debt levels would eventually implode under inevitably rising bond yields (and hence debt costs).

For literally decades, Wall Street mavericks were betting big on a yield spike that would re-crush the Nikkei and JGB in one big headline.

But this headline never came, and the foregoing bet against Japan became known on the Street as the "widow maker."

Buying Time, Postponing Pain

Instead, the BoJ bought itself decades of time and a market recovery by printing just unthinkable levels of yen to keep JGBs (Japanese bonds) bought and the Nikkei higher.

For the near entirety of my career, this kept Japanese yields at zero to negative, buying time while crushing those who bet against Tokyo.

Which brings me back to that boring 4.18% record yield on the 30Y JGB.

This figure confirms that the dam has finally broken on the broken Japanese "plan."

Or to use the analogy above, the canary in its coal mine just died.

For those paying attention, these rising yields just caused the Nikkei 225 to lose 200B in a single day, and this sell-off was led by the so-called "Immortal" tech kings, you know, the kind which were never supposed to fall - like AOL, Yahoo or Cisco of old.

The Sickness is Global and Currency-Killing

But what happens in Tokyo doesn't stay in Tokyo.

Yields across the "developed" world have been rising to decade highs because the bond markets are now showing more honesty than central bankers, from Tokyo to DC.

As the yield on the Bloomberg Global Sovereign Bond Index shoots past 3.72%, yields from Australia and the UK to Germany and the USA are skyrocketing to untenable levels.

The bond market is essentially asking for more risk premium (yield) on government IOUs that are no longer trusted.

Given this global debt fiasco, is it therefore any surprise that the global broad money supply of printed paper currencies, which hit $150 TRILLION in June, has increased by a staggering 50% since 2020?

Such open currency debasement now hiding in plain sight not only explains why currencies like the USD have lost 87% in absolute purchasing power since decoupling from gold in 1971, it further explains why the world's central banks are stacking gold at an unprecedented pace in 2026.

Physical gold is no longer an allocation or dollar "debate"; it is the open and now obvious puck direction of global collateral and the de facto international reserve asset above tanking currencies and unloved sovereign IOUs.

This is not fable but fact.

Stocks vs. Gold

But equally worth noting from the Japanese tech sell-off of late is what it reminds as to the dot.com era of yesterday and what it portends for the AI era/market of tomorrow.

Unlike the aforementioned bloodbath during the internet bubble, today's U.S. stock market is literally being kept alive by an equally game-changing technology meme with an even greater profile of over-investment ($400B this year alone by the leading tech names), which always moves from over-bought to over-sold.

With U.S. public debt crossing 40T as rates rise to levels costing Uncle Sam (i.e. you) over $3B/day to service the interest expense, the convergence of a credit crisis is about to slam into a dying PE market, an already dead private credit market and an over-valued and over-hyped AI sector.

This suggests that what we just got a glimpse of in Japan (as to both its markets and currency) is an undeniable warning of what is to come to the U.S. NASDAQ and dollar.

Be Prepared

Timing this convergence is a mug's game. Preparing for it is not.

Even if central banks like the Fed or BoJ "save" the markets with mouse-clicked trillions, the currency destruction necessary to support those "resilient" markets is robbing you in plain sight.

The Nikkei, for example, has seen an impressive 145% gain in the last five years, yet when measured in gold terms, the result was a net loss of -31%.

During that same period, the NASDAQ 100 has shown an impressive nominal return of 95%, yet when measured in gold, the net result has been a loss of -23%.

And if any of you were being told by your advisors over the last 12 years that USTs were the key to your safe retirement, the "risk-free returns" of Uncle Sam's IOU, when measured against gold, have lost you 90%.

See the theft? See the real measure of wealth?

Given the foregoing interplay of rising rates, tanking bonds, debased currencies and hyper-risk in the tech sector, an allocation to physical rather than paper gold is the only asset separating the informed from the uninformed, and the wealth-protected from the wealth-destroyed.

Tyler Durden Wed, 09/09/2026 - 17:00

Elon Musk's PAC Bets Trans Issue Push Will Drive GOP Voters To The Polls

Elon Musk's PAC Bets Trans Issue Push Will Drive GOP Voters To The Polls

Elon Musk's America PAC has opened its 2026 midterm ad campaign with a barrage of ads centered on trans issues. Musk has reportedly authorized the PAC to spend more than $100 million this cycle and is targeting four Democratic Senate candidates in competitive races: Sherrod Brown in Ohio, Josh Turek in Iowa, James Talarico in Texas and Mary Peltola in Alaska. They are running online and across streaming platforms, marking the first coordinated trans-focused push of the cycle from a major Republican-aligned outside group.

Photograph: Michael Swensen/Getty Images
According to AdImpact, the firm that tracks political ad spending, trans issues have been a minor theme in GOP Senate advertising so far this cycle. America PAC's opening salvo changes that calculus, and it arrives as Republicans navigate a difficult midterm environment, with voters across party lines angry over the Iran war and the high gas prices that have followed it. Economic concerns dominate what voters tell pollsters they want candidates to address. Trans and LGBT issues barely register on those same surveys.

So, why try this now? The answer traces back to the final weeks of the 2024 presidential campaign, when a similar ad devastated Kamala Harris's presidential campaign. Trump's closing spots successfully cast Kamala Harris as out of touch because of her support for taxpayer-funded gender transitions for prison inmates and illegal immigrants, culminating in the line "Kamala is for they/them, President Trump is for you."

Democrats have not disputed the ad's effectiveness, even in hindsight. Quentin Fulks, Harris's principal deputy campaign manager, said after the election that even though trans issues sat "at the bottom for voters," trailing the economy, immigration, crime and inflation in what people actually cared about, the "Kamala is for they/them" line effectively branded Harris as "out of touch."

According to a report from Semafor after the election, Democratic Party allies had expected it to "flop or backfire," but instead, "it inspired more than $215 million of follow-up ads, by multiple campaigns, dividing Democrats and fulfilling the Trump campaign's goal of branding Harris as an out-of-touch progressive."

That explains why America PAC is reaching for the same playbook now, and public opinion data suggests this still can be an effective strategy.

Gallup found in 2025 that 66 percent of Americans want a person's birth sex listed on documents such as passports and driver's licenses, versus 31 percent who favor listing current gender identity. Sixty-nine percent told Gallup they favor requiring transgender athletes to compete on teams matching their biological sex. Pew Research Center found nearly identical numbers on athletics, 66 percent in favor and just 15 percent opposed, with support up 8 points since 2022. A separate Pew survey published Aug. 11, 2026, found 73 percent of respondents uncomfortable, to varying degrees, with transgender athletes competing on teams that do not match their biological sex. On gender transitions for minors, Pew found 56 percent favor making it illegal for health-care professionals to provide gender-transition treatment to people under 18, up 10 points since 2022.

Whether pivoting midterm messaging to the culture war pays off depends on a variable the 2024 campaign did not have to contend with: an electorate frustrated with Republicans over the Iran war and the prices that have followed it. Trans messaging worked in 2024 as an addition to an economic argument that heavily favored Trump. America PAC is banking on it working again in this cycle as a substitute for one.

Tyler Durden Wed, 09/09/2026 - 16:40

"You Better Get Ready For... War": Socialists Call For "War In The Streets" & The End Of Capitalism

"You Better Get Ready For... War": Socialists Call For "War In The Streets" & The End Of Capitalism

Authored by Jonathan Turley via JonathanTurley.org,

"You better get ready for ... war."

Across the country, radicals are openly planning for the next stage of their movement, and notably, the Democratic establishment is not part of their plans.

Despite the talk of a "Big Tent Party," socialists are riding high on a surge of support and talking purges and revolution.

In Chicago, radicals gathered for a conference on Marxism during what many view as the heyday of socialism in the United States. The Democratic Socialists of America is now larger and more powerful than at any time in our history. Socialist candidates are winning elections across the country as Democratic establishment figures from Sen. Chuck Schumer (D., N.Y.) to Gov. Gavin Newsom pander to the movement.

Speakers in Chicago used the conference to push supporters to the next stage in the movement, including some openly calling for violence and the end to capitalism.

University of California Santa Barbara History Professor Butch Ware said Democrats "must be destroyed" and urged attendees to be ready for "war in the streets." Notably, in postings on X, Ware has said that candidates such as New York City Mayor Zohran Mamdani and Senate nominee Abdul El-Sayed are too restrained and are being pushed by the establishment "to contain radicalism."

The professor "of Africa and Islam" whose faculty page is appropriately found under "bware" is the latest radical to dismiss the "Big Tent Party" rhetoric of establishment figures like Schumer. He declared, "The Democrats cannot be reasoned with. They must be destroyed." There is little subtlety in the message, Ware has explained: "You cannot call yourself a revolutionary and not be talking about training with weapons."

It is another example of the delusion that establishment Democrats have that they will be able to use these radicals to destroy their political enemies but not themselves.

After one election victory, socialists chanted "You're Next!" when House Minority Leader Hakeem Jeffries's image came on big-screen televisions.

Hasan Piker has called for a purging of moderates from the Democratic Party.

Just last week, Darializa Avila Chevalier declared, "A big tent doesn't pay your rent, lower your grocery bill, or take on the corporations bleeding our country dry. Democratic socialism does."

In a video posted to X, Professor Ware called for violence, warning followers that "some of these clickety-clack revolutionaries have never been in a f*cking gunfight." He menacingly added, "Y'all ain't nowhere near ready for a war in the streets. You better get ready for both kinds of war if you stay ready, you ain't got to get ready."

This is just the latest example of the type of hate-spewing radical that university departments want to teach in higher education. While purging virtually all Republicans, conservatives, and libertarians from departments, faculty candidates cannot be too radical enough to secure positions on colleges and universities. UCSB pays Professor Ware over $211k to spread this type of lunacy.

Notably, this is the same university that saw a professor lead her students in physically assaulting pro-life advocates on campus years ago. Despite pleading guilty to criminal assault, she was not fired and later honored by the University of Oregon for her inspiring leadership.

In other events around the country such as "Socialism 2026 Conference," City University of New York Professor Ruth Gilmore said in a video, "It's capitalism we're after,...There isn't a capitalism that is somehow not racial. There isn't a capitalism that does not produce and reproduce all kinds of sexual and gender boundaries."

At my alma mater, University of Chicago professor Eman Abdelhadi, the half-sister of Michigan Democratic Senate candidate Abdul El-Sayed, has denounced the university and explained that she is only teaching there to bring down the system.

One year after the massacre, Professor Abdelhadi offered an "October 7th blessing" over an attack that murdered, raped, and tortured innocent men, women, and children. She was previously arrested for spitting on officers.

She added "I hope you know that we have a lot of work ahead of us and that we need each other to do that work. We have an imperative to not just imagine a better future, but to build one together. I'll see you on the streets."

What is so striking is that these radicals are not hiding their agenda or their hostility toward the Democratic Establishment. William Lawrence, who is running for Michigan's 7th Congressional District, previously called for the end of borders, the nation-state, capitalism, and told a leading moderate Democrat to "hurry up and die."

In the meantime, some Democrats are admitting that, after using the socialists to retake power, they will marginalize them in actual governing decisions. Rep. Laura Gillen (D-NY) just explained that they will have to block the "crazy" DSA stuff from actually getting to the floor for a vote.

In Rage and the Republic, I discuss how these Democratic leaders are following the same self-destructive delusions of other establishment figures in history who thought that they could use mobs against their opponents while hoping that they could survive.

Figures like Newsom have even campaigned on denouncing capitalism as "not working" as candidates like Texas Democratic Senatorial candidate James Talarico have called to "dismantle" capitalism. Figures like former Vice President Kamala Harris have dismissed loyalty to our core institutions such as the Supreme Court as mere "nostalgia."

It will not work. These figures are nothing more than "clickety-clack revolutionaries" who convince no one inside or outside the movement. By putting their elections above every other consideration, Democratic leaders are willing to endanger core institutions, values, and even capitalism itself to reacquire power. In so doing, they are embracing the very "mobocracy" that the Founders warned us against in laying the foundations of our constitutional system.

Tyler Durden Wed, 09/09/2026 - 16:20

US Students Still Behind Much Of The World In Math And Reading: Global Assessment

US Students Still Behind Much Of The World In Math And Reading: Global Assessment

Authored by Aaron Gifford via The Epoch Times,

Results from a recent global assessment indicate that reading scores for American high school students have dropped over the past three years, while math and science performance still falls behind their peers in several other developed countries.

The Program for International Student Assessment (PISA), which tests 15-year-olds in math, science, and reading proficiency as metrics for college and career readiness, conducted its last tests in 2025.

The initial findings, released on Sept. 8, indicate that children from Singapore, Japan, South Korea, Australia, Canada, and the United Kingdom continue to outperform American public-school children in those three subjects.

PISA has not yet shared comprehensive comparative rankings of the 91 nations that participated in the latest assessments.

China did not participate as a nation; the four Chinese provinces that did also outperformed American 15-year-olds.

About 760,000 children across the world participated, according to the PISA website.

All told, U.S. students still performed above the average of all participating nations in reading and science, and slightly below average for math.

Compared to the 2022 PISA, average U.S. results in science remained the same.

For math and reading, however, the average scores remained below pre-COVID levels and "among the lowest ever observed in PISA in the United States" dating back 26 years.

Education Secretary Linda McMahon said the nation's outdated public education needs a major overhaul that begins with universal school choice for all American families.

"The United States of America is a nation built to lead the world, yet our one-size-fits-all federal education bureaucracy has shortchanged our children and stifled our future," she said in an email to The Epoch Times.

"Today's international education scores confirm a decade of stagnation and a devastating gap: we successfully propel our highest achievers, but the lowest-performing students are falling further behind - and have suffered a loss of learning in reading equivalent to nearly a year and a half of instruction compared to 2015.

"This moment is a stress test for our nation's future. To pass it, we must enact a hard reset that stops protecting a failed status quo and instead builds a system that empowers state leaders and embraces innovative learning options through school choice."

The PISA proficiency levels range from one to six, with level two considered minimum proficiency.

Seventy-four percent of the U.S. students were at level two or above in reading, but only 13 percent were at level five or six.

The results for science were similar.

For math, 65 percent of U.S. students were at level two or above, but only 8 percent were at levels five or six, compared to 54 percent of the four Chinese provinces and Singapore's 37 percent.

The 2025 program introduced a digital computational problem-solving assessment.

U.S. children scored above the overall average in that category, still falling behind several Asian and English-speaking nations, but outperforming Germany, France, Mexico, and Brazil, according to the PISA report.

Globally, PISA determined that one in five students is considered low-performing in science, math, and reading, up from 16 percent in 2022.

Average reading scores fell by 28 points since 2015, while math fell by 22 points, according to the report.

"PISA 2025 shows that reversing declines in student performance is urgent," said Mathias Cormann, secretary-general of the Organization for Economic Cooperation and Development, which oversees the PISA program.

"The most successful education systems focus on fewer areas in greater depth, invest in teachers, engage parents, and provide targeted support for the students and schools that need it the most," Cormann said in the report.

"Technology and AI can strengthen learning and help prepare young people for the future, but only when used purposefully and not as a substitute for attention, effort, and understanding."

PISA also surveyed participants about their use of artificial intelligence to draft text in writing assignments and determined that those who did not use it outperformed those who said they did.

Tyler Durden Wed, 09/09/2026 - 15:50

Comcast Plunges As CFO Warns Broadband Subscriber Bleeding Won't Stop

Comcast Plunges As CFO Warns Broadband Subscriber Bleeding Won't Stop

Comcast shares tumbled after CFO Jason Armstrong warned at the Goldman Sachs Communacopia + Technology Conference that broadband subscriber losses would not improve this quarter from a year earlier.

Bloomberg first reported Armstrong's comments, which sent shares down as much as 8.1% around 11:16 a.m. ET, their largest decline in months.

Armstrong told the audience at the conference in San Francisco, California, today that he still expects broadband subscriber losses to improve for the full year, although quarterly results will vary. He blamed part of the pressure on what he called "irrational fiber pricing."

Analysts tracked by Bloomberg expected Comcast to lose 103,000 domestic broadband subscribers in the third quarter, slightly fewer than the 104,000 lost a year earlier.

KeyBanc analyst Brandon Nispel expects consensus subscriber forecasts to deteriorate following the comments. He said, "We would expect CMCSA consensus net adds to move lower, where an accelerating loss trajectory could require further ARPU pressure for Subs to stabilize, a cycle we don't see ending."

Charter Communications fell 5.7% as the warning weighed on peers.

Tyler Durden Wed, 09/09/2026 - 15:05

FCC Chairman Says Agency May Issue Guidance On 'Fake Polls' Ahead Of Midterms

FCC Chairman Says Agency May Issue Guidance On 'Fake Polls' Ahead Of Midterms

Authored by AG News Staff via American Greatness,

Federal Communications Commission Chairman Brendan Carr said the agency may soon issue guidance to television broadcasters over what he called "fake polls," particularly if they are intended to suppress voter participation ahead of November's midterm elections.

Carr said Sunday that broadcasters face federal public-interest obligations because local television stations use FCC-licensed public airwaves, unlike cable networks and online platforms.

"There's a lot of interest right now in fake polls that are out there," Carr said. "And so the FCC may put guidance out soon to remind broadcasters about their obligations with respect to not airing fake polls, particularly if they're done to suppress people heading into the fall."

Carr's comments follow criticism from President Donald Trump over media coverage of political polling and his endorsement record in Republican primaries.

Trump recently called for the FCC to take action against NBC News' Kristen Welker after she said on a local NBC affiliate that Trump had experienced "mixed results" with candidates he endorsed in this year's primaries.

Trump disputed that characterization and said Welker should be reported to the FCC for "rebuke or punishment."

NBC News defended Welker.

Carr did not announce a formal investigation of Welker.

Instead, he said the FCC was considering several actions involving broadcasters and emphasized their obligation to operate in the public interest.

The FCC regulates local broadcast television and radio stations, but its authority over news content is limited by federal law and the First Amendment. The commission has historically said it generally will not intervene in complaints about one-sided or inaccurate news coverage because doing so could improperly substitute the government's judgment for that of broadcasters.

FCC Commissioner Anna Gomez, the commission's sole Democrat, rejected the idea that the agency can punish individual journalists over their reporting.

"As I've said many times, the FCC has no authority to punish journalists this administration doesn't like," Gomez said.

Carr has not specified what standards the FCC would use to determine whether a political poll is "fake" or what consequences broadcasters could face under any new guidance.

Tyler Durden Wed, 09/09/2026 - 14:50

Scarcity Warnings In Physical World Send Commodities To 14-Year High, Threatening Stock Rally

Scarcity Warnings In Physical World Send Commodities To 14-Year High, Threatening Stock Rally

Readers are familiar by now with the broad-based commodity rally, with energy, agricultural products and metals moving sharply higher as former Goldman Sachs commodities head Jeff Currie warned this summer of growing scarcity in the physical economy.

The Bloomberg Commodity Index has climbed to levels last seen in 2012...

... while the Quantix Commodity Index has hit a new record high.

Bloomberg macro strategist Simon White is out with a new note this morning warning that the commodity rally is threatening to squeeze corporate margins and household spending, raising questions about how long stocks can withstand an inflation shock spreading well beyond oil.

White wrote:

Stocks are reacting negatively to the inflation and growth risks from commodities, which have just reached levels not seen since 2012.

Commodities are rallying, but this is no longer principally an oil story. The rally is instead broadening out. Since the beginning of August, not only are energy prices rising, such as European gas (up 34%), or gasoline (+22%), metal prices are also rising (zinc, copper), as well as precious metals (silver, platinum, gold), and softs, such as sugar, cocoa and corn.

He added:

Only a handful of the main commodities traded on futures markets (eg hogs, cattle, nickel and orange juice) are down since Aug. 1.

The energy shock affects input costs for everything from manufacturing to food production. The hobbling of refinery capacity from the Iran war has led to elevated prices for products such diesel and gasoline, inflaming transport costs.

Soft commodity prices are being further pressured by the escalation of the Russia-Ukraine war, especially in the Black Sea region, as well as concerns about a particularly potent El Nino this year and next.

For equity bulls, White warned that soaring commodity prices raise questions about how long stocks can withstand an inflation shock broadening across the commodity complex. 

He continued on that thought:

The recent rally in raw materials has taken the Bloomberg Commodity Index to near 15-year highs. On a 10-year annualised basis, returns recently reached a level they have only once eclipsed, in 2008, since the mega-commodity rally of the 1970s.

But as we can see from the chart above, when commodity prices are high, such as in the 1970s or early 2010s, stock prices falter. Equivalently, stocks tend to enjoy their best periods when commodities are historically on the low side.

The current environment of rising stock and commodity returns looks somewhat of an anomaly. Stocks are slipping today, but if commodity prices stay bid - and there are many reasons for them to do just that - the equity market has more downside ahead. (Tatiana's point on higher energy prices boosting earnings won't translate into higher stock prices if the rest of the economy is suffering from broad-based commodity inflation.)

The Nasdaq 100's ratio to the Quantix Commodity Total Return Index has pointed to this summer's renewed commodity outperformance as traders price in scarcity. 

As we've pointed out in the metals space, copper is at an all-time high, north of $14,700, and iron ore might have found a bottom, with prices in Singapore around $100 a ton. On the critical materials side, we've outlined the continued tightening of supplies from China to the West, as seen last week in a Reuters report. We've also identified miners that are poised to break China's "quasi-monopolistic" grip on critical materials.

Tyler Durden Wed, 09/09/2026 - 14:35

3rd Burning Man Attendee Dies En Route To Hospital

3rd Burning Man Attendee Dies En Route To Hospital

Authored by Jill McLaughlin via The Epoch Times,

A third person has died at this year's Burning Man Festival in the Nevada desert, according to the local sheriff's office.

Details about the death, reported on Sept. 8, were not released as festival attendees faced the usual traffic jam on their way home from the annual event in Black Rock Desert about 110 miles north of Reno.

The death occurred en route to a Reno-area hospital on Sept. 4, according to the Burning Man Project.

"We are saddened to have learned that a Burning Man participant, who experienced a serious medical emergency in Black Rock City during the early hours of Friday, Sept. 4, and immediately received on-site lifesaving measures, later passed away after being transported to Reno for medical care," a festival spokesperson told The Epoch Times in an email.

The examiner overseeing the death investigation at the Washoe County Medical Examiner's Office didn't return requests for more information.

Two other festival attendees died this year at the weeklong event that started on Aug. 30.

On Sept. 3, the first man, identified later by Sheriff Jerry Allen as Sampson Tshombe, was pronounced dead by a doctor on festival grounds.

"It is with heavy hearts that The Burning Man Project confirms a Black Rock City participant in his mid-50s experienced a medical emergency, immediately received lifesaving measures, and was transported to the onsite center for emergency care where he was pronounced deceased," the organization said of Tshombe in a statement.

Two days later, the festival reported Craigh Mann, 60, was found dead by his friends at his camp at about 3 p.m.

Mann was also sent to the Washoe County Medical Examiner's office for an autopsy and toxicology screening, according to the sheriff.

Allen reported deputies had arrested 34 people for drug sales and trafficking at this year's festival as of Sept. 5.

Requests sent to the sheriff to confirm the arrest information were not returned by publication time.

An average of one death a year is reported at the annual festival that typically attracts about 70,000 people to its temporary sand metropolis.

Last year, 37-year-old Vadim Kruglov, of Russia, was found dead at the event. Sheriff's deputies, who were investigating the death as a homicide, have not yet made any arrests.

[ZH: We have one question, while we know they went out dusty, did they go out smiling?]

Tyler Durden Wed, 09/09/2026 - 14:05

Pages